
Clover University
Expert guides and resources to help newcomers, rebuilders, and savers navigate the path to Canadian homeownership.
How Does Rent-to-Own Work in Ontario? A Plain-Language Guide
Learn how rent-to-own works in Ontario, step by step: the 5% option deposit, monthly payments, term length, red flags, and how you buy the home.
How to Rebuild Your Credit to Qualify for a Mortgage
Declined for a mortgage? Here are the ten steps to rebuild your credit, what score A-lenders want to see, and how long it really takes.
Rent-to-Own Success Tips: What Families Who Actually Buy Do Differently
Rent-to-own works when it's built around one goal: mortgage approval. Here's what the families who actually close do differently, from day one.
You're Closer to Owning Than You Think
Most Canadians overestimate how far they are from homeownership. Here's why the gap is smaller and more solvable than you've been told.
5 Actions to Take After Starting a Rent-to-Own
Signed a rent-to-own agreement? Five things to do now, paperwork, maintenance, a real budget, a repair fund, and credit repair that actually works.
What You Should Know Before You Start Shopping for a Home in Canada
Six things to settle before you open a single listing plus the two Canadian rules (the stress test and closing-cost cash) most checklists get wrong.
Can You Actually Fix Your Credit? Here's What Nobody Tells You
No company can legally remove accurate negative items from your credit report and the Government of Canada agrees. Here's what actually works, whether you have collections or not.
Waiting for the Perfect Time to Buy Could Keep You Renting
Waiting for rates, credit, or savings to line up has a cost. Here's how to compare three more years of renting against a structured path to a mortgage with rent-to-own.
Can You Get a Mortgage During a Consumer Proposal?
A family filed a consumer proposal after COVID layoffs. Here's the two-clock timeline that decides when they can actually qualify for a mortgage.
How Much Does Homeownership Cost Per Day?
The $13-a-day comparison is the most abused number in rent-to-own. Half of it is honest. Here's which half and how to stress-test it against your budget.
How Do You Get Mortgage-Ready in Canada? A Barrier-by-Barrier Roadmap
Credit, down payment, closing costs, self-employment, a consumer proposal, or a new Canadian credit file. Find the barrier stopping you, and how long the fix takes.
You Have the Income, so Why Won't the Bank Approve Your Mortgage?
Strong income. Down payment saved. Still declined by the bank? Learn why mortgage approvals fail and how we help Canadians get into homeownership.
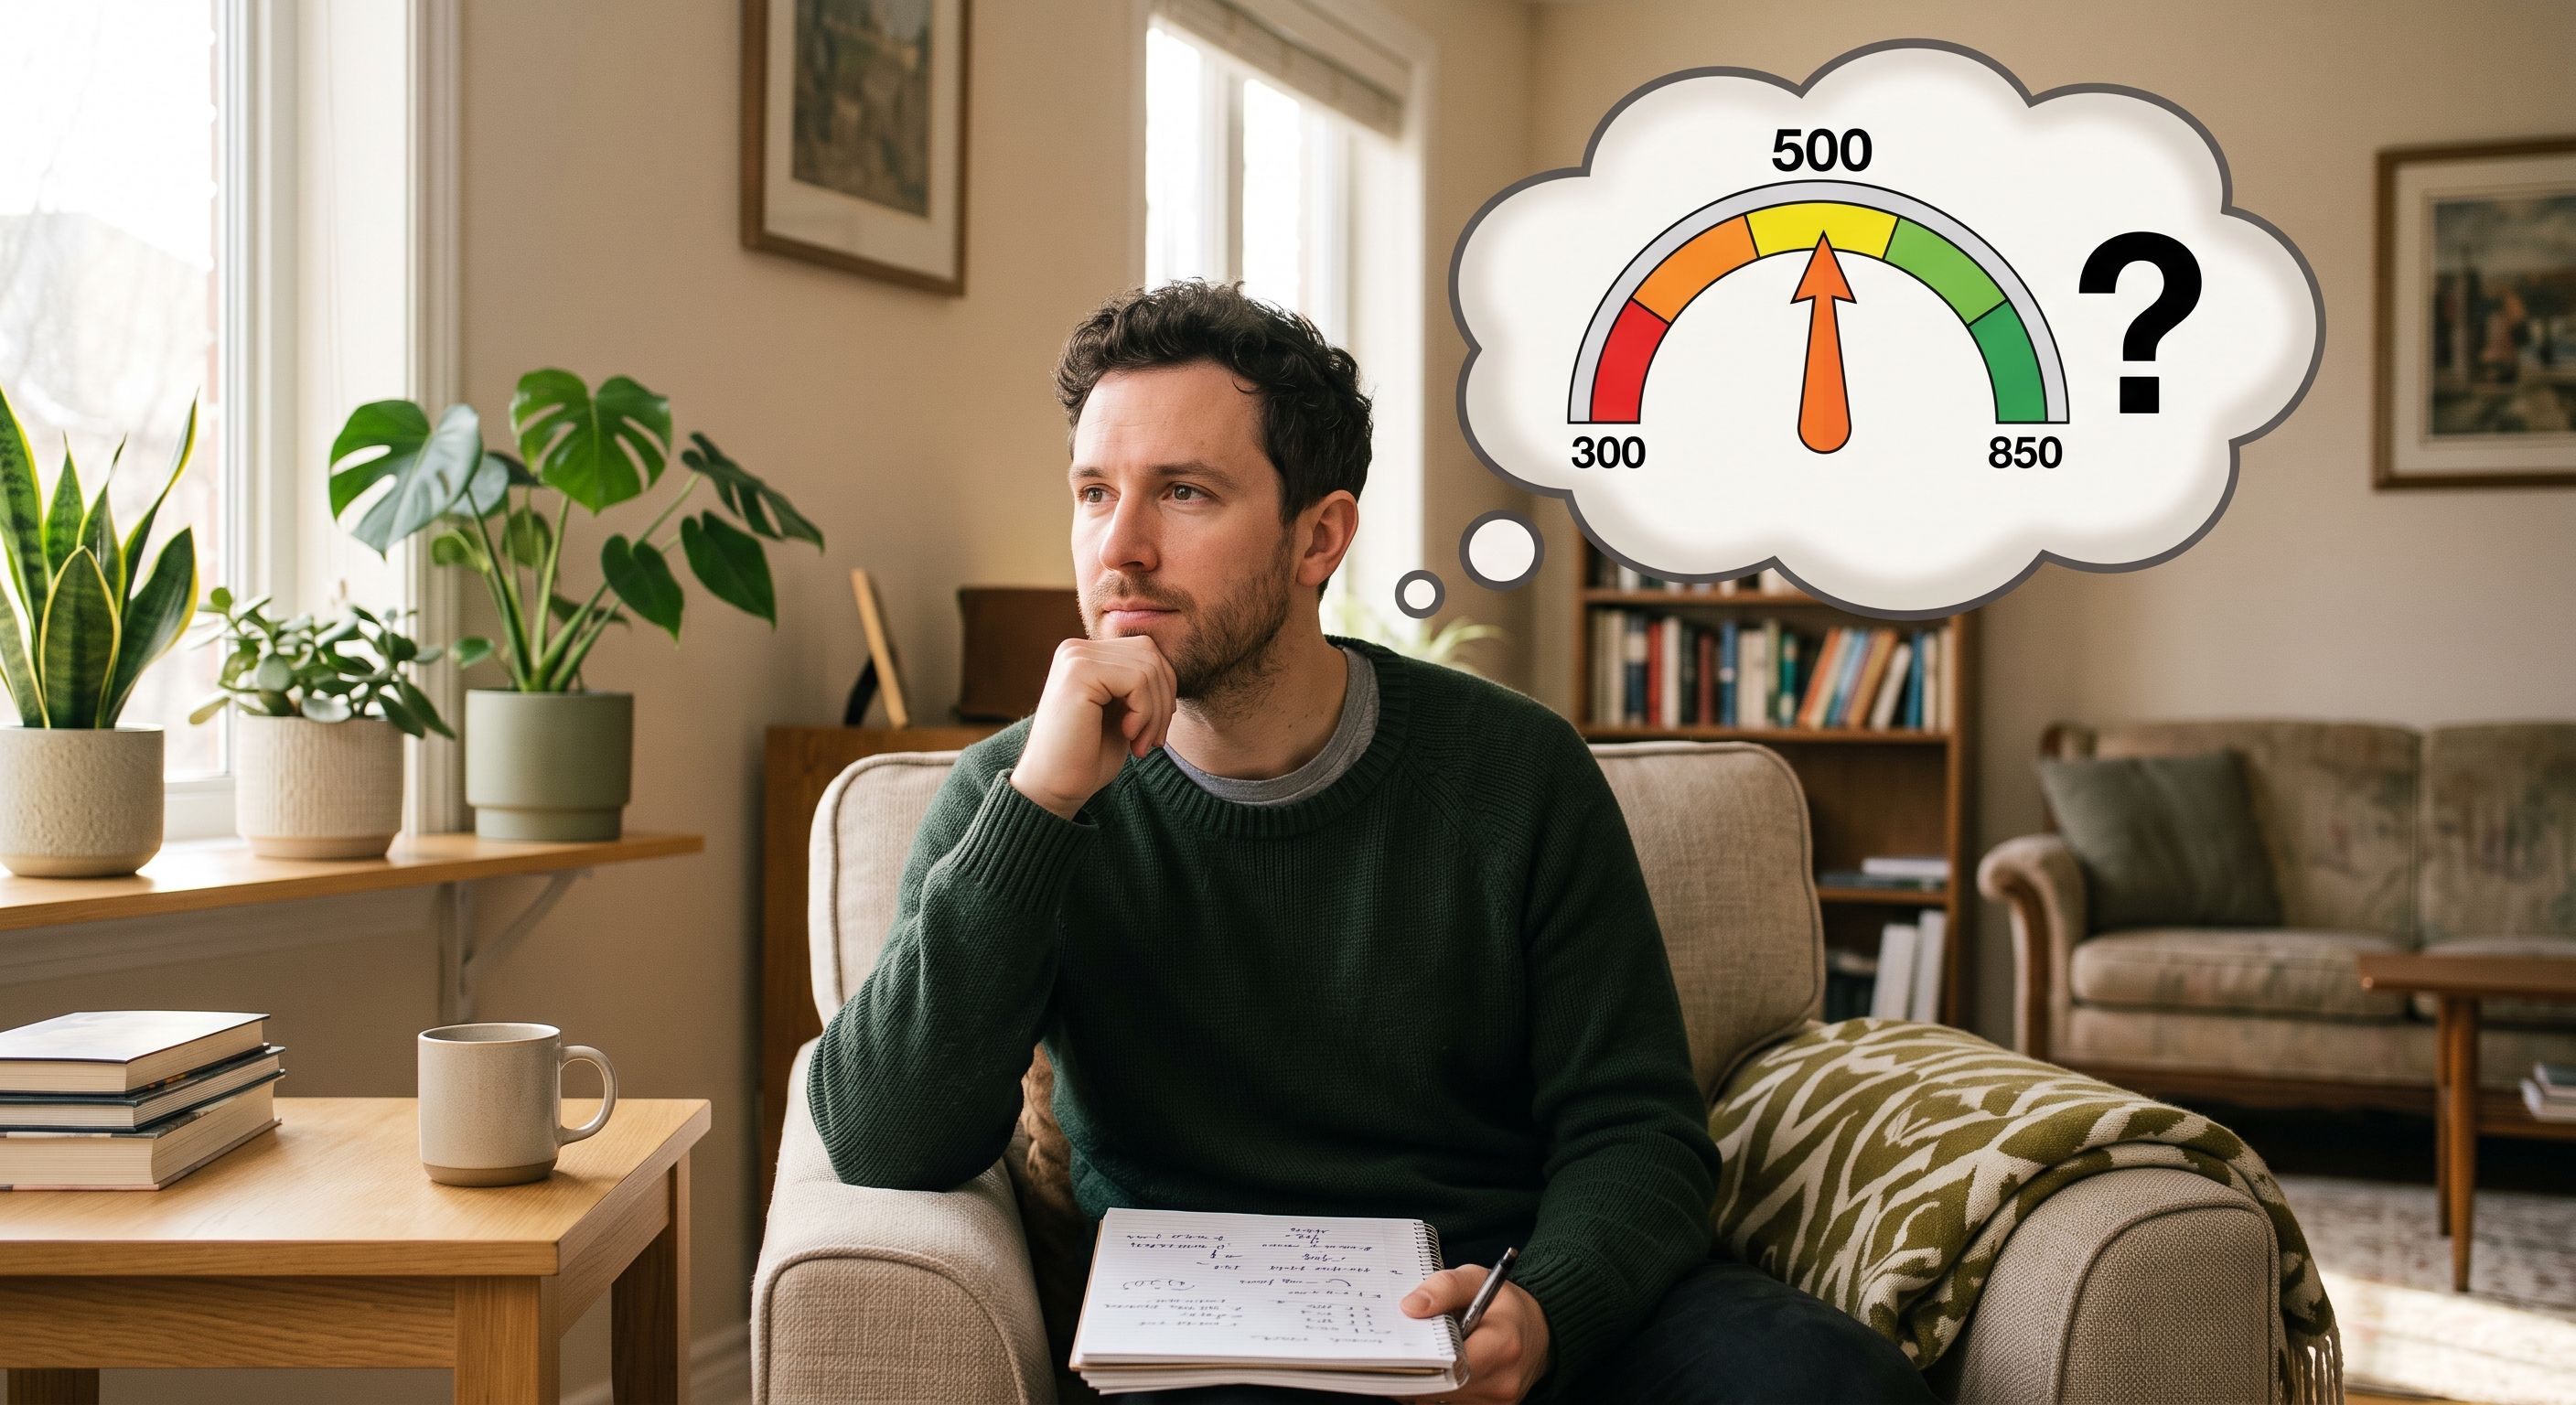
You Can Qualify for Rent-to-Own With a Credit Score as Low as 500!
Rethink Renting accepts credit scores as low as 500. Here's why the bank's 680 wall doesn't apply — and the five things to fix during your term.
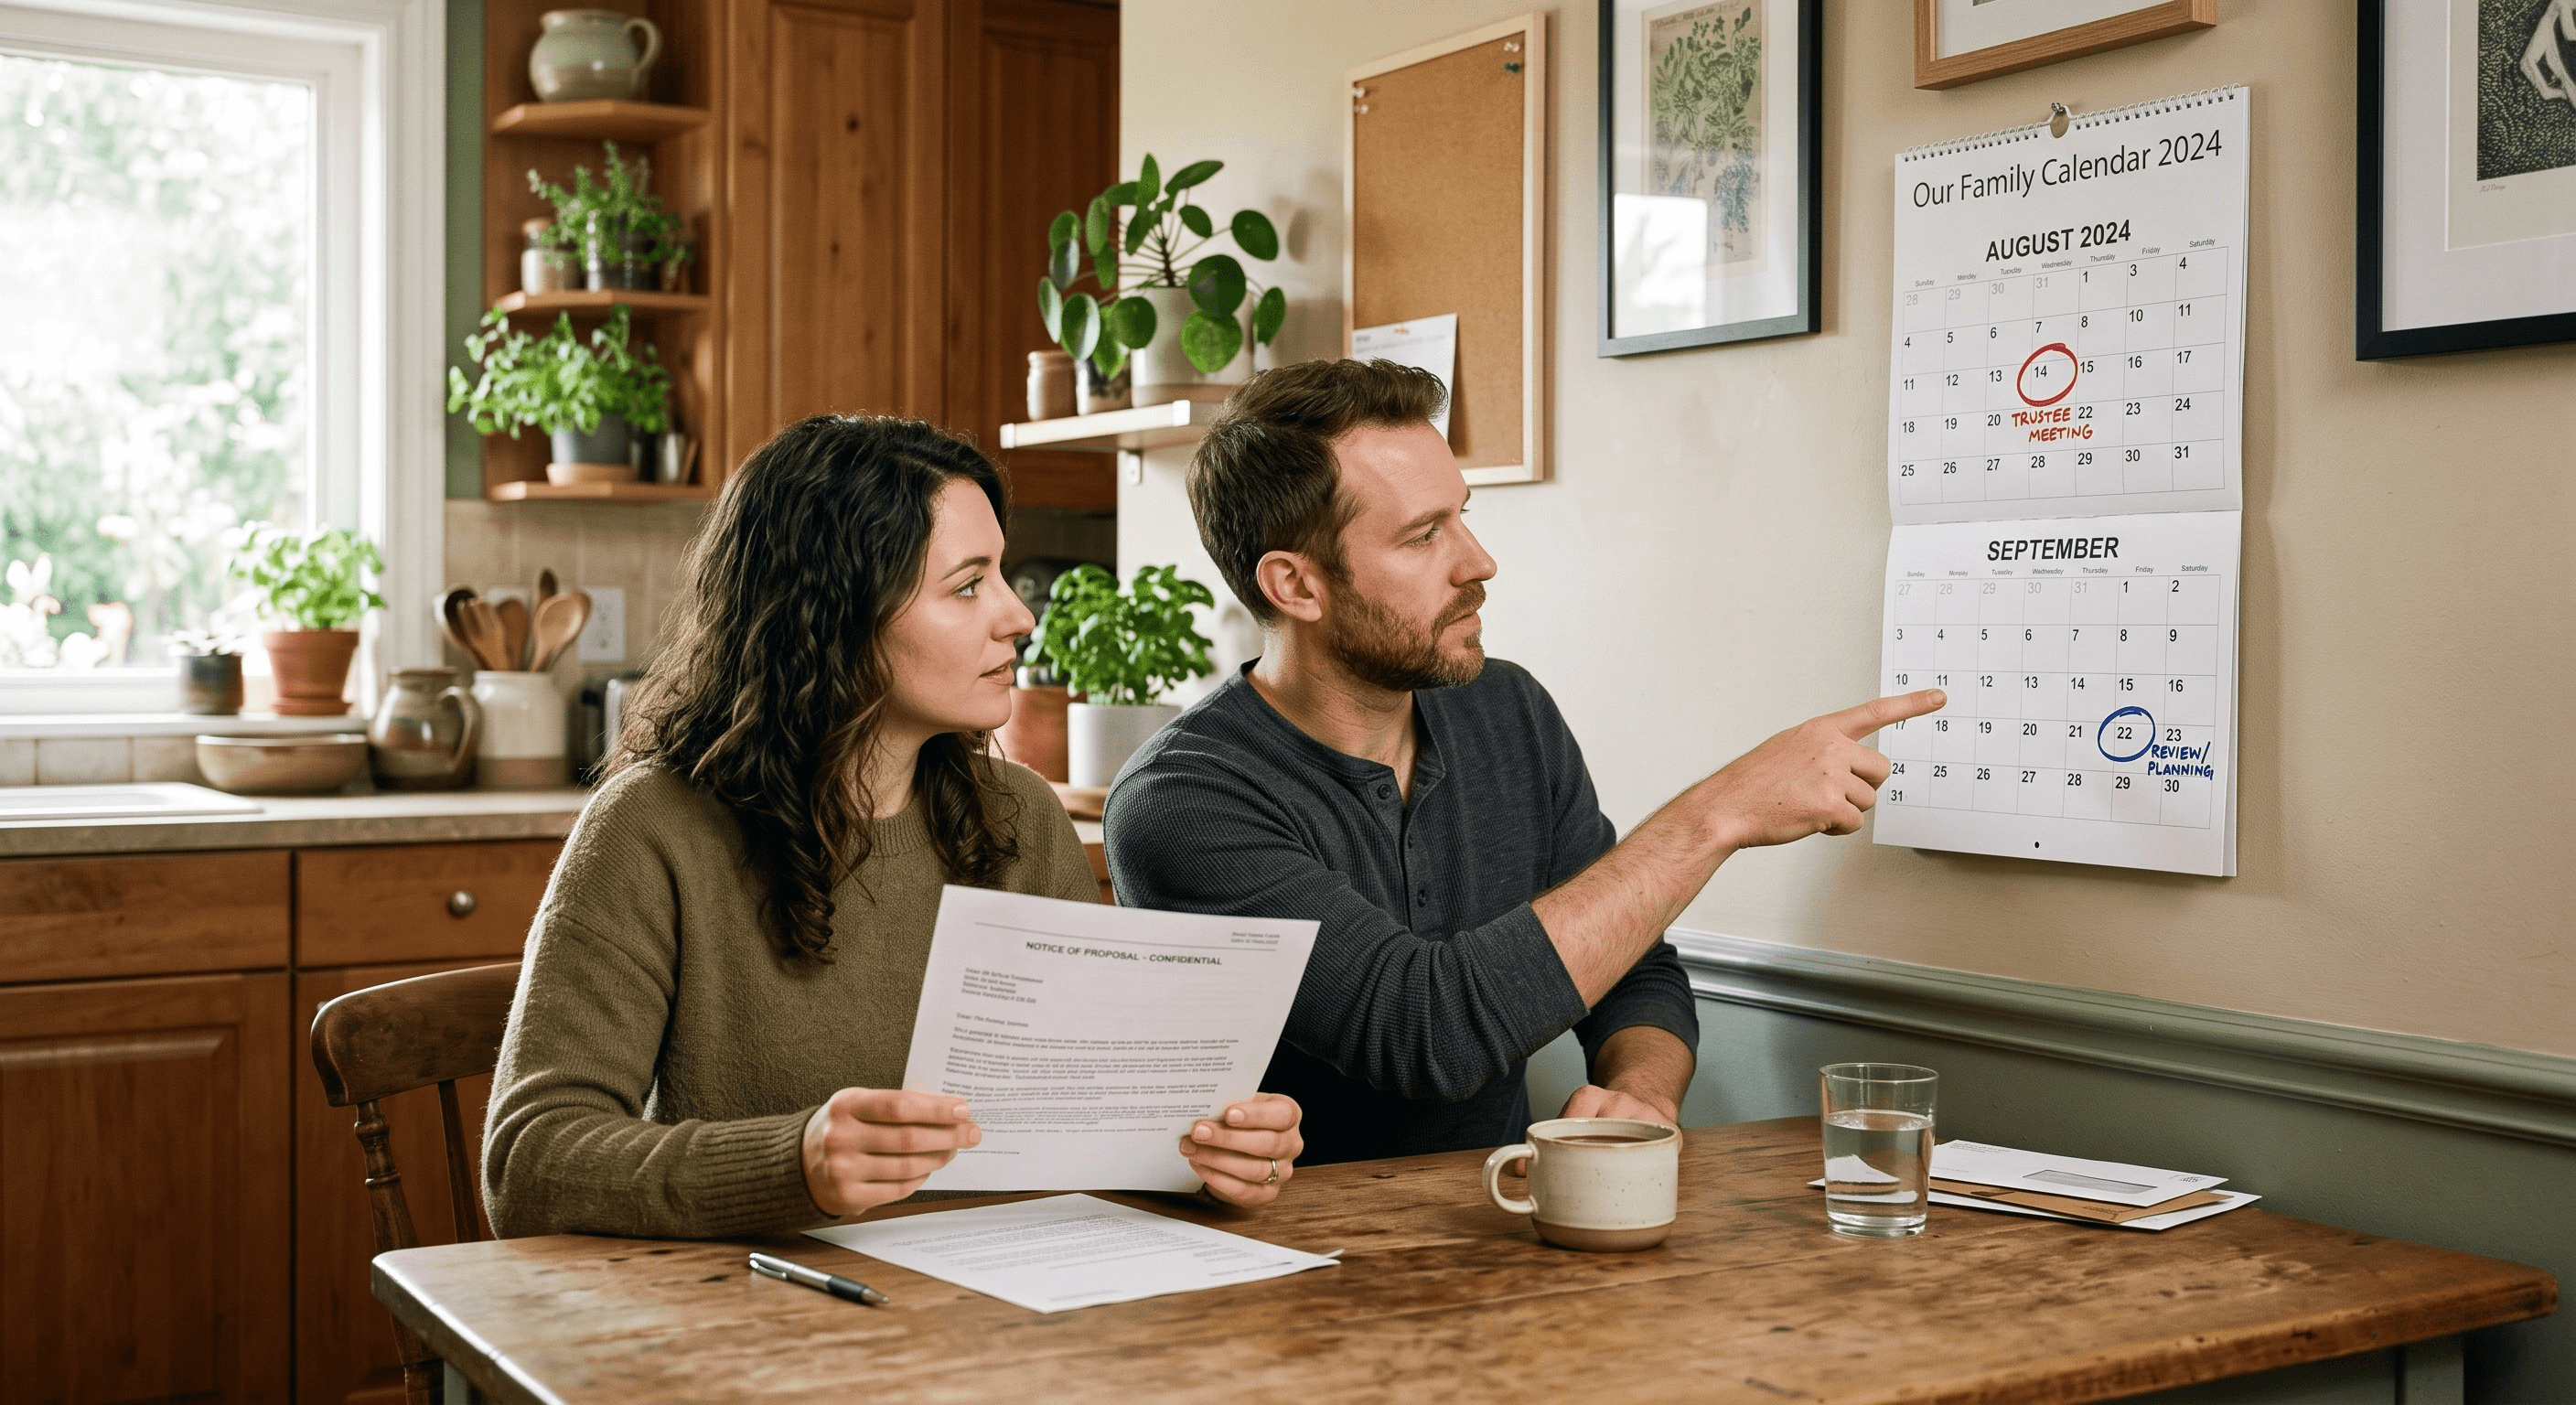
The Consumer Proposal Timing Trap: Why Your Rent-to-Own Term Shouldn't End When Your Proposal Does
Most A-lenders want 12 to 24 months of clean credit after your consumer proposal is discharged. If your rent-to-own term ends the same year, you have no runway and your option deposit is what's at risk.
What Is Causing the Housing Issues in Canada?
Canada's housing problem is really three problems at once. CMHC data on first-time buyers, stressed mortgage holders and seniors shows why.
Equity Sharing vs. Rent-to-Own: Why a Locked-In Price Hurts
Traditional rent-to-own locks your purchase price years early. Equity sharing doesn't and puts a portion of the market's gains into your down payment instead.
Rent-to-Own vs Renting and Saving: Which Path to Homeownership Is Right for You?
Choosing between a rent-to-own agreement and traditional renting while saving for a down payment can significantly impact your path to homeownership. This comprehensive guide breaks down both options to help you make an informed decision.
How Much Home Can You Afford in a Rent-to-Own Program?
Learn how Clover uses Canada's mortgage stress test to set your rent-to-own budget — so you can actually exit into a mortgage when your program ends.
Private Mortgage vs Rent-to-Own: The Safer, Cheaper Path to Homeownership
Not all mortgage alternatives are equal. Here's the hard truth about some private lenders—and why rent-to-own may be the smarter, safer path to owning your home.
Your Top 5 Questions About Rent-to-Own, Answered Honestly
Most people look into rent-to-own and don't move forward. They have the same five concerns. This guide addresses each one directly, no spin, no pressure, so you can make the right decision for your household.
How Does an Equity-Sharing Homeownership Program Work?
Equity sharing lets you move into a home now and buy it later but it isn't free money. Here's exactly how the equity, the title and the exit work.
Understanding Rent-to-Own: 10 Steps to See If It's Right for You
Learn how rent-to-own works in 10 steps: from calculating affordability to scheduling your first call with Clover. An honest guide for rebuilders, newcomers, and savers.
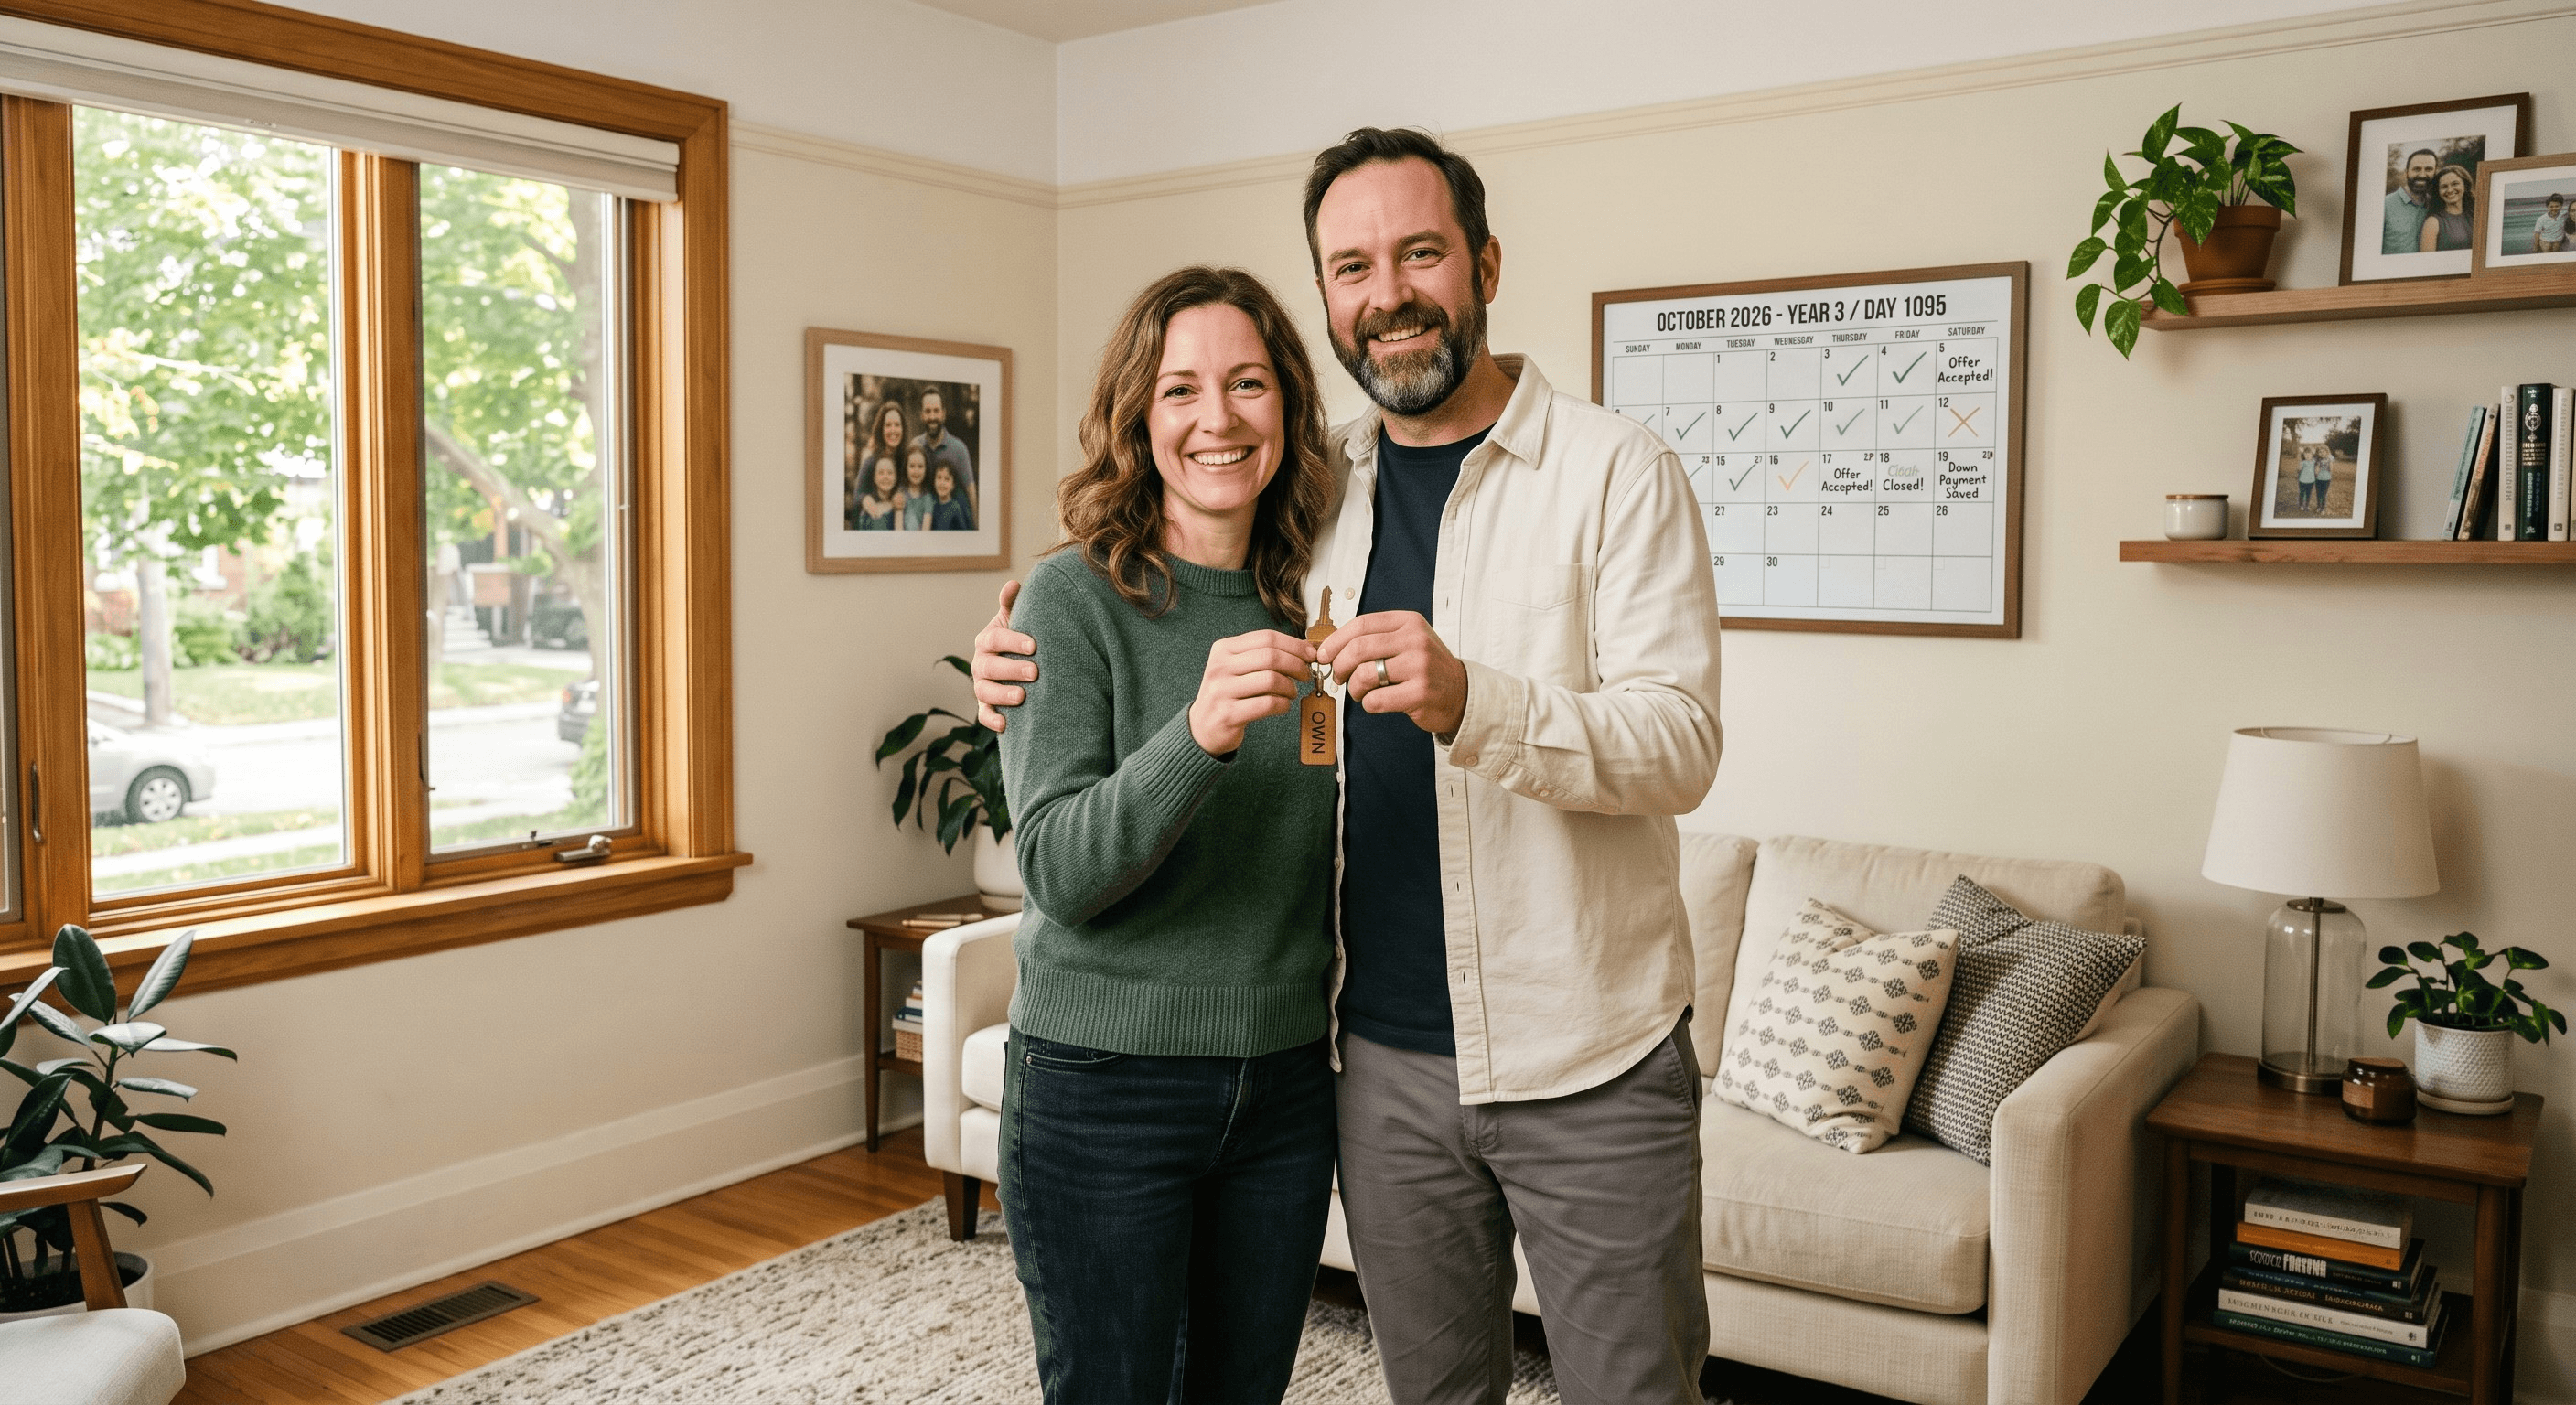
From Renting to Owning: Michael and Danielle's Three-Year Journey
A family unable to qualify for a mortgage stayed in their home and became owners by using rent-to-own to build the credit and financial profile their lender required.
When Is Rent-to-Own a Good Idea?
Rent-to-own isn't right for everyone — but in the right situation, it's a powerful path to homeownership. Here's how to know if it fits yours.
The Biggest Risk in Rent-to-Own Isn't the Contract, It's the Future Homeowner Not Being Ready
Most rent-to-own deals don't fail because of bad contracts, they fail because buyers aren't mortgage-ready when the term ends. Here's why.
5 Ways Rent-to-Own Is Like Homeownership Training
Rent-to-own trains you for mortgage-style payments, maintenance, budgeting, down payment growth, and exit planning before you buy a home.
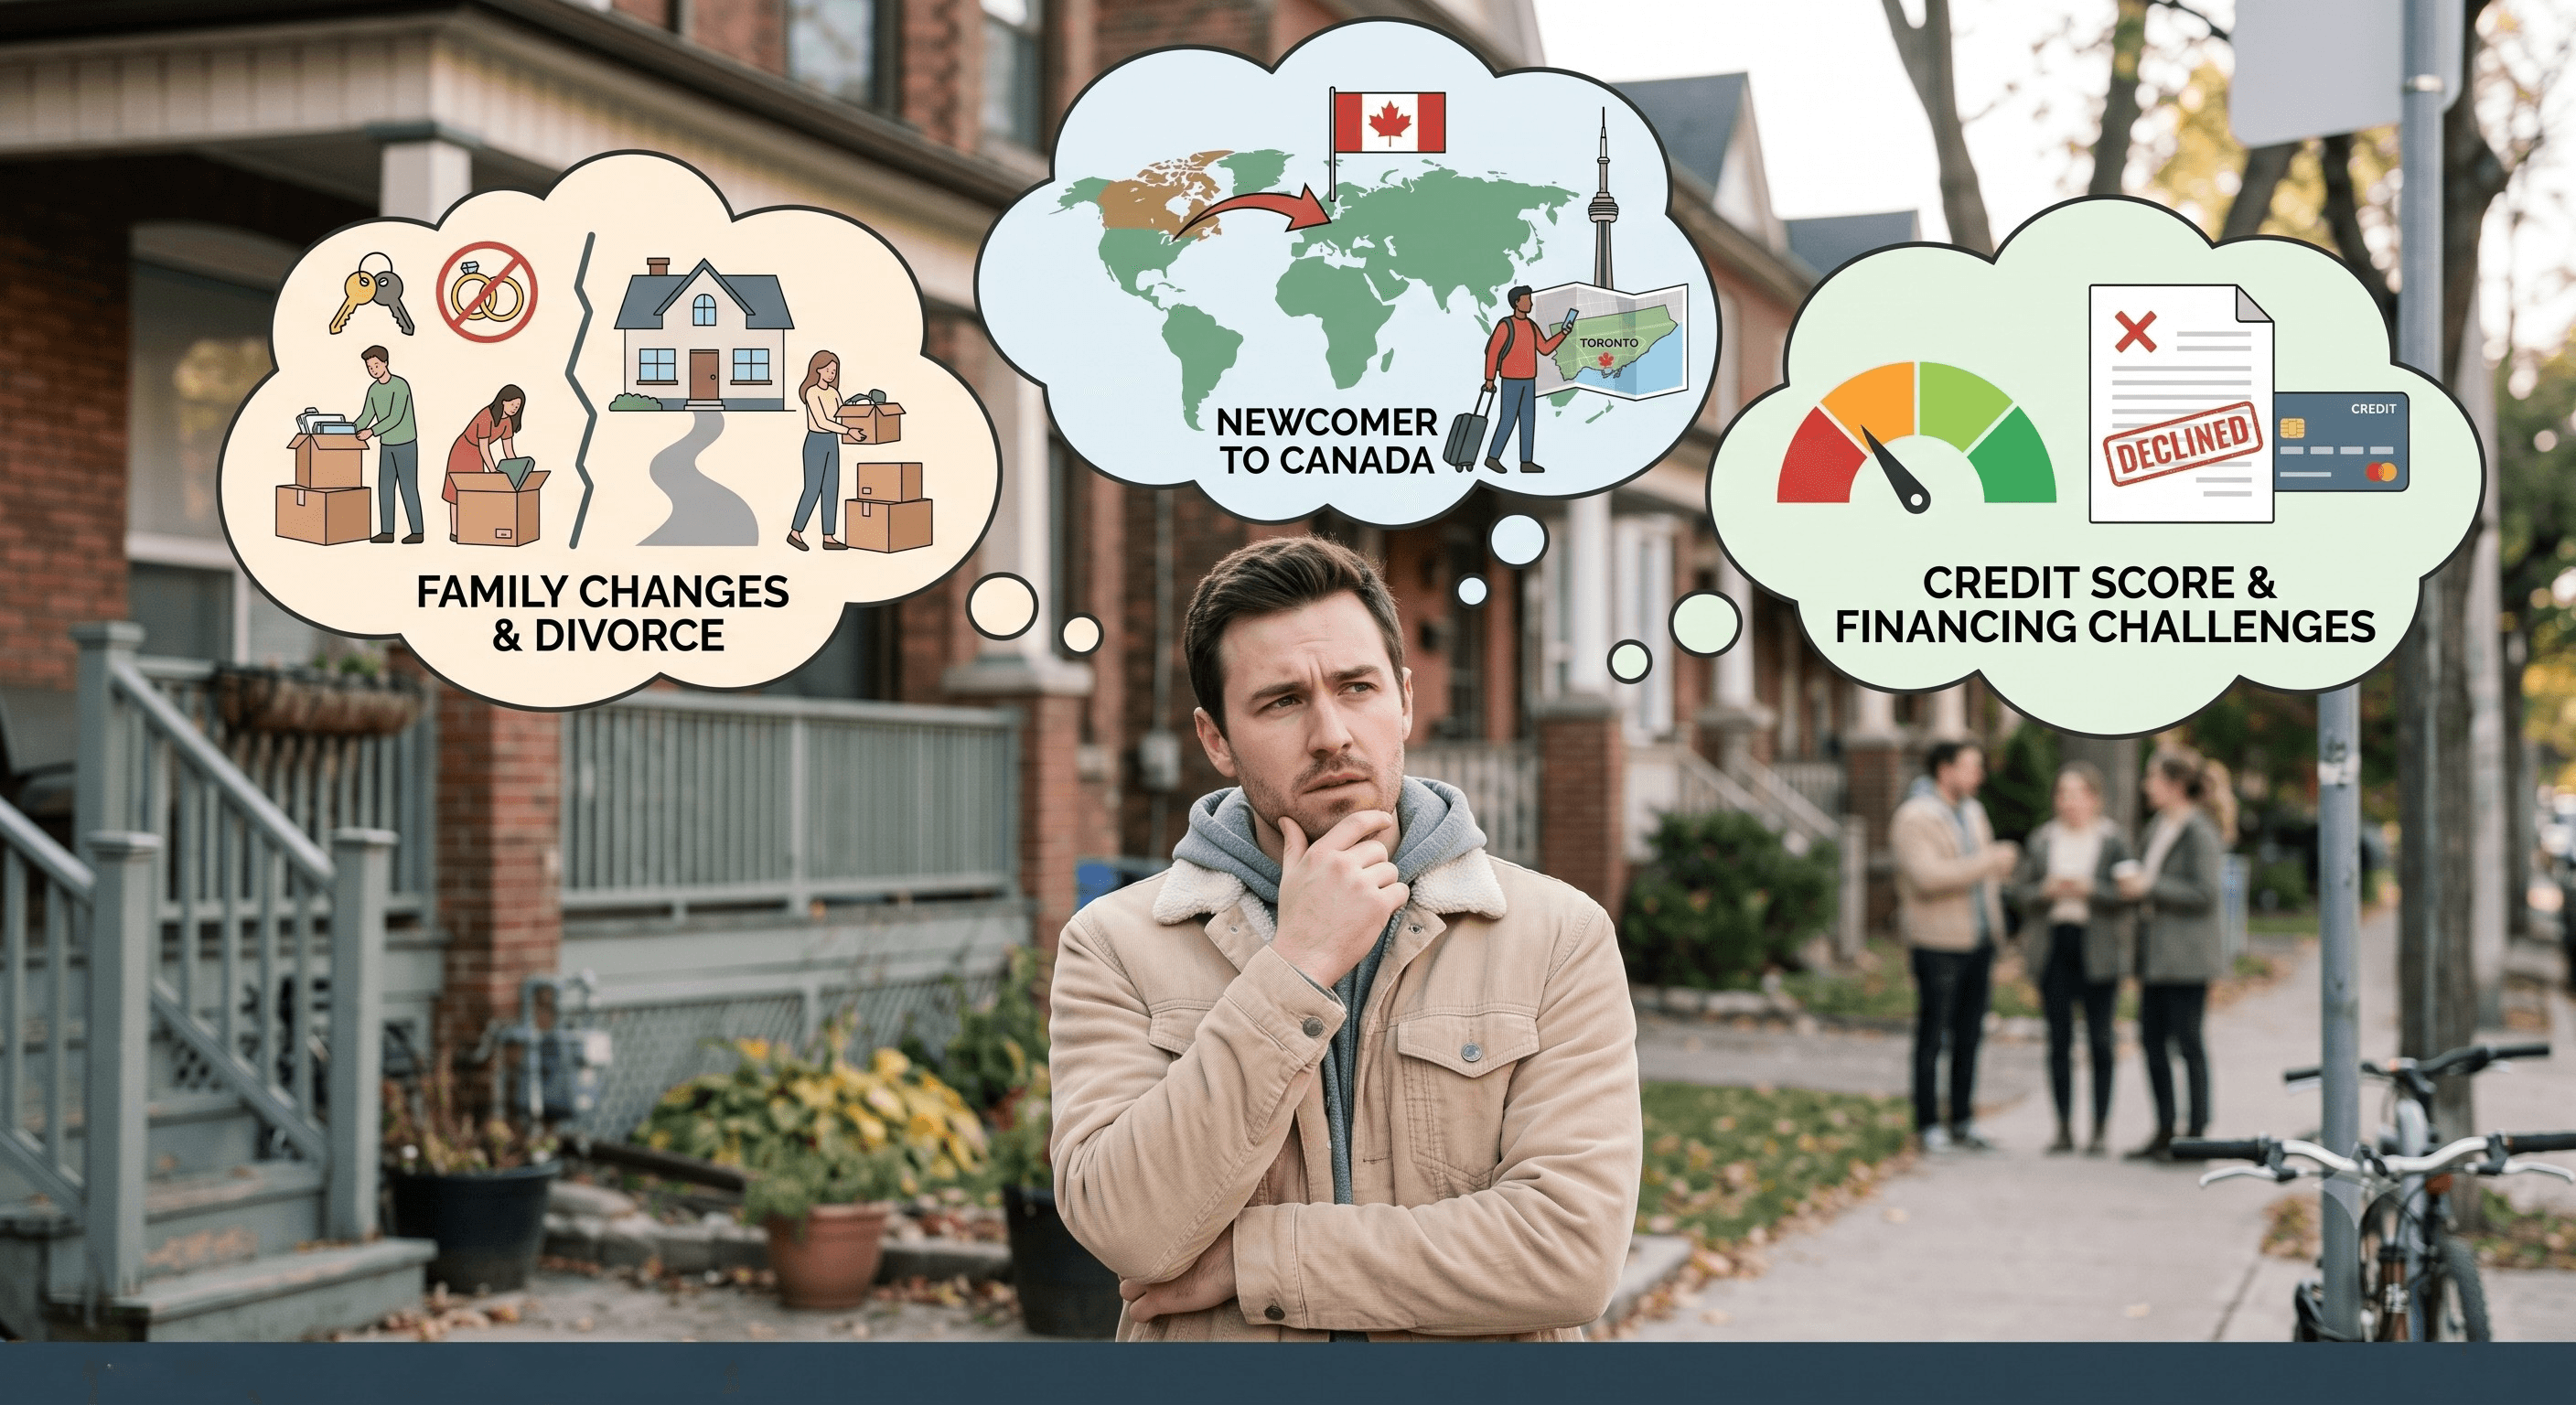
5 Life Events That Can Derail a Mortgage Without Making You a Bad Buyer
Divorce, a job change, self-employment, newcomer status, and a consumer proposal don't make you a bad buyer, just one who needs more time.
5 Ways Rent-to-Own Helps You Become Mortgage-Ready
Rent-to-own builds mortgage readiness through payment history, structured savings, credit-repair time, exit planning, and stress-test-calibrated payments.
Can You Buy a Home After Divorce With Damaged Credit?
A divorced couple got declined for a mortgage, then moved into their 4-bedroom home through rent-to-own while rebuilding credit on a set timeline.
From Newcomer to Homeowner: A 3-Year Plan That Actually Works
Canada's mortgage system wasn't built for newcomers. Here's a structured 3-year plan that closes the gap and gets you to conventional homeownership.
Why Banks Decline Good Buyers: 5 Real Reasons in Canada
Solid income, bills paid on time and still declined? Here are the 5 real reasons Canadian mortgage applications get rejected, and how each one is fixable.
Trying to Get Mortgage-Ready? These 5 Things Usually Slow Buyers Down
Bruised credit, closing costs, debt, income documentation, and down payment size are the 5 things that usually slow buyers down on the road to a mortgage.
Does Rent-to-Own Fit You? A 7-Point Qualification Checklist
A quick 7-point checklist to see if rent-to-own fits your income, savings, credit timeline, and homeownership goals in Ontario or Alberta.
5 Rent-to-Own Lessons Learned Since 2009
A licensed mortgage pro shares 15 years of hard-won rent-to-own lessons. What works, what fails, and who actually succeeds.
The Hidden Cost of Waiting to Buy a Home: The Double Whammy
After a mortgage decline, waiting costs you twice: rent builds zero equity while home prices climb. Here's the math and how to stop both clocks.
5 Things Most People Get Wrong About Rent-to-Own
Rent-to-own gets misunderstood constantly. Here are five myths that trip people up and what's actually true.
Rates Are Falling in Canada. Why Are Buyers Still Stuck Renting?
Interest rates are falling in Canada, but qualifying is still the real hurdle. Here's how rent-to-own bridges the readiness gap to a real mortgage.
Rent to Own vs. Mortgage: Which Is Right for You?
A mortgage is almost always the better path to homeownership — but what if you can't qualify yet? Here's how the two options honestly compare.
Why Was I Declined for a Mortgage? 3 Real Reasons (and What to Do)
Declined for a mortgage in Canada? The real reason is usually one of these three things, credit, a thin newcomer file, or self-employed income. Here's each fix.
Do You Really Have to Wait Two Years After a Mortgage Decline?
A mortgage decline isn't a two-year sentence. See how rent-to-own lets you move into a home you choose now and build toward owning it.
Declined for a Mortgage? Here's What It Actually Means
A mortgage decline isn't a verdict on you, it's a rigid system saying no to one file. Here's what it really means and the options banks don't mention.
Is Renting Throwing Money Away? The Math Most People Avoid
Two years of renting can mean $57,600 gone with zero equity. See the real math and how an equity-building path to homeownership changes the ending.
The Harkins Family: Saved From a Last-Minute Closing Crisis in Hamilton
How a Hamilton family nearly lost their $40,000 deposit to a private mortgage they couldn't close — and how Clover stepped in to save the deal.
The Real Cost of Renting: What Nobody Tells You
Renting looks cheaper on paper — but what does it actually cost you long-term? Here's the calculation most renters never run.
Are Banks the Only Way to Buy a Home in Canada? A Case Study
Six years of bank declines, zero mention of alternatives. How one Ontario family finally became homeowners through rent-to-own.
From Renting to Homeowner: How the Wessens Did It With Rent-to-Own
One Ontario family saved $35K but couldn't qualify for a mortgage due to a car loan. Here's how rent-to-own changed everything.
Would I Recommend the Ownable Program for Someone I Love?
Neil Oliver answers the one question that cuts through the marketing: would he recommend Ownable for his own family? Here's his honest answer.
Is Rent-to-Own a Scam? How to Spot a Legitimate Program
Learn the red flags of a unsavoury rent-to-own program and what a legitimate, structured program in Canada actually looks like.
The 3 Types of Buyers Who Succeed in Rent-to-Own
Not everyone succeeds in rent-to-own but the ones who do share three clear traits. Find out which type of buyer you are through this article.
Do You Want to Rent for Four More Years or Own While You Save?
The only question that really matters isn't about affordability, it's about direction. Two futures, same starting point. Which one are you building?
5 Key Success Factors for Rent-to-Own in Canada
Clover Properties has found a success blueprint for Rent-to-Own in Canada. Here are the 5 factors that separate renters from owners.
The Ultimate Guide to Rent-to-Own in Canada (2026 Edition)
Learn exactly how rent-to-own works in Canada — costs, timelines, who qualifies, and how to spot a legitimate program.
The Honest Truth About Rent-to-Own in Canada
Most RTO companies won't say this: a bank mortgage is always better. Here's when rent-to-own makes sense and how to spot the real thing.
Renting vs. Rent-to-Own: A Dollar-for-Dollar Comparison Over 3 Years
We ran the real numbers on a $600K home — renting vs. rent-to-own over 3 years. The difference in where you end up financially might surprise you.
How the Hellickson Family Saved Their Purchase with Rent-to-Own
The Hellicksons had an accepted offer but couldn't cover closing costs. Here's how rent-to-own saved their purchase and made them homeowners finally.
How Much Down Payment Do You Actually Need? The Hidden Costs
5%? 10%? 20%? Plus closing costs, reserves, and more. Here's the real cash you need to buy a home in Canada.
The Habits That Make Rent-to-Own Actually Work
Most people in rent-to-own don't fail from bad luck, they fail from treating it like a lease. Here are the six habits that get buyers to the closing table.
Turn "Not Yet" Into "Move-In Ready"
Mortgage denied? Canadians with stable income and 4–5% saved may still reach homeownership through a structured rent-to-own alternative.
Why Rent-to-Own Companies Use the Stress Test to Set Your Budget
Think your rent-to-own budget should be bigger? Here's why the stress test sets your ceiling and why that's a major thing that protects you at exit.
Is Rent-to-Own Actually a Good Idea?
Rent-to-own has a bad reputation, some of it earned and some of it misinformation. Here's an honest look at when it genuinely works, and when it doesn't.
Why Rent-to-Own Requires a Down Payment and Why That Helps You!
Your option deposit isn't a fee, it's the foundation of your mortgage exit. Here's how it builds equity and gets you to homeownership.
How New Canadians Can Buy a Home Without Canadian Credit History
No Canadian credit history? Here's how rent-to-own lets newcomers move in, build credit, and buy their home — all at the same time.
Bad Credit? Here's Your Real Roadmap to Owning a Home
Think bad credit locks you out of homeownership? Here's the honest breakdown — and a step-by-step path forward.
Falling Behind on Mortgage Payments? How Refinance Rent-to-Own Can Help
If you're struggling with mortgage payments or trapped in a high-rate private mortgage, Refinance Rent-to-Own could help you keep your home, reset your payments, and start fresh.
Why Rent-to-Own Payments Are Higher
Rent-to-own payments are higher than traditional mortgages but not because it's a premium. Here's the real math behind the difference.
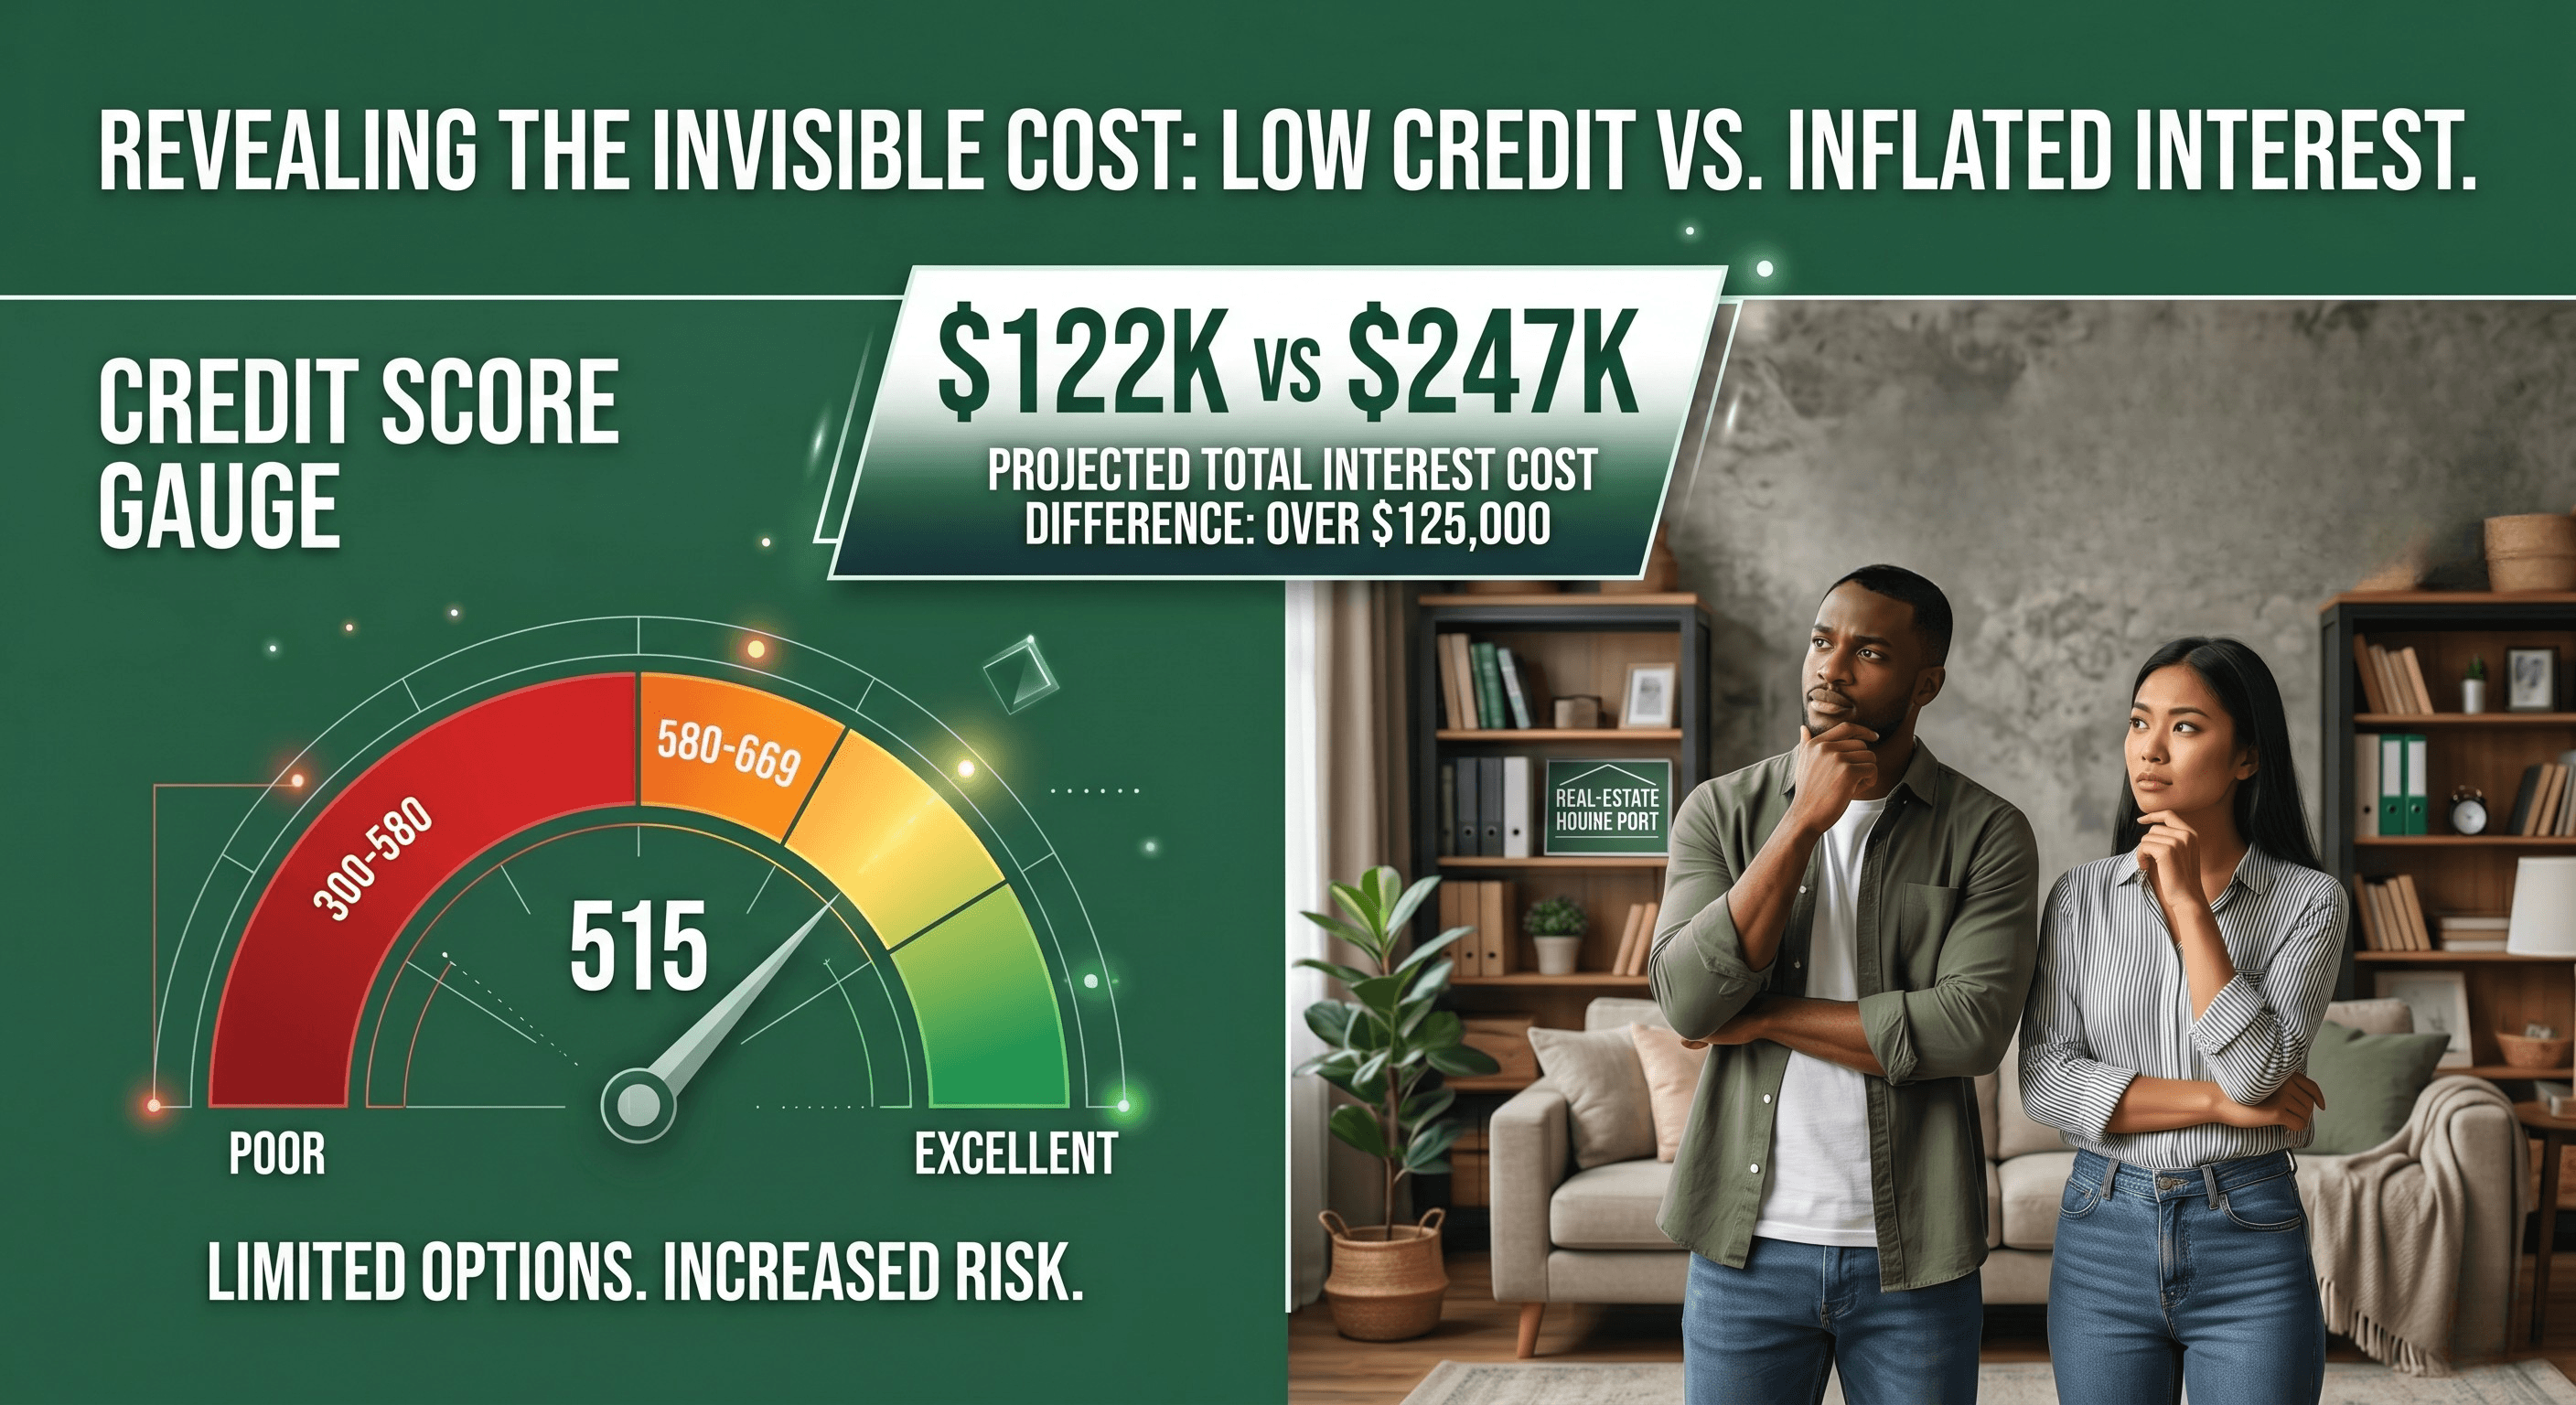
How Much Does Your Credit Score Affect Your Mortgage Rate in Canada?
Your credit score doesn't just nudge your mortgage rate, it determines which lender tier will work with you. Here's what the difference actually costs in dollars, and how to close the gap.
More Homes, More Power: What Elevated Inventory Means for Buyers Who Aren't Quite Ready Yet
Housing inventory sits 49% above the 10-year March average — and that shifts negotiating power to buyers. Here's how to use this market window if you're not mortgage-ready yet.
The Bank Said No. Your Dream Didn't Have To
Two mortgage declines didn't stop one Edmonton family. Here's how rent-to-own became their path to a home they now own, with equity.
Rent-to-Own Isn't About Housing, It's About Identity
Rent-to-own success isn't about the numbers, it's about the mindset. Here's what separates the families who make it to mortgage from those who don't.
You're Watching the Housing Market But You're Not In It
Prices are softening and opportunities exist — but the bank still says no. Here's why waiting to qualify may be the riskiest move you can make.
What Happens in Year 2 of a 4-Year Rent-to-Own (That No One Talks About)
Everyone talks about getting in. No one talks about living it. Here's what Year 2 of rent-to-own really looks like and how to stay on track.
First-Time Homebuyer Programs in Ontario (2026)
Every major government program Ontario first-time buyers can use in 2026 like FHSA, RRSP, and closing cost rebates explained plainly and stacked.
The Biggest Lie in Real Estate: "Just Save More"
Saving is good advice until it becomes a trap. Here's why "just save more" is keeping Canadian buyers stuck, and what to do instead.
Why Your Rent-to-Own Purchase Price Is Higher Than Today's Price
The future purchase price in a rent-to-own isn't a program quirk — it's just how real estate markets work. Here's what that really means for you.
Can You Lose Your Down Payment in Rent-to-Own?
Worried about losing your deposit if rent-to-own doesn't work out? Here's what's actually at risk and how a good program protects you.
Where Does Your Money Actually Go in a Rent-to-Own Program?
Worried your rent-to-own payments are just disappearing? Here's exactly where every dollar goes and how it's building toward the home you want.
Why You Need a Down Payment — Even in Rent-to-Own
Think rent-to-own skips the down payment? It doesn't, it builds toward one. Here's why it exists and how Clover helps you get there.
Is Now the Right Time to Buy a Home in Alberta?
Alberta inventory is up 38% and buyers finally have room to negotiate — but the spring market could close that window faster than you think.
Why Right Now May Be the Best Time to Buy in Ontario
Ontario home prices are down 7% and inventory is up — giving buyers rare negotiating power before the spring market shifts things fast.
Best Budget Advice for Canadians Saving for a Home
An honest budget playbook for finding hidden money, cutting smarter, and building your down payment faster than you think possible.
How Much Do You Need to Start Rent-to-Own in Ontario or Alberta?
Thinking about rent-to-own but unsure what it costs upfront? Here's a plain-English breakdown with real numbers for $500K–$700K homes in Ontario and Alberta.
Mortgage Readiness Timeline: Exactly When to Start Preparing
Most Canadians need 3-12 months to get mortgage-ready. Here's exactly what to do each month to avoid rejection and get the best rate.
Rent-to-Own vs Renting: Why You're Not Getting Ahead as a Renter
Every month you pay rent, someone else builds equity. Here's the math on what you're losing and how Rent-to-Own flips the script.
What to Do When the Bank Says No: Your Rent-to-Own Options Explained
Been declined for a mortgage? A bank's "no" isn't the end. Learn how Rent-to-Own keeps your homeownership dream alive with a structured path to approval.
Why Your Credit History Doesn't Transfer to Canada (And What to Do About It)
New to Canada? Your excellent credit from home doesn't count here. Learn why you start at zero and exactly how to build Canadian credit fast.
Work Permit vs PR: What Actually Qualifies You for a Mortgage in Canada
High income but no PR? Here's what Canadian banks actually require for mortgage approval, and how Rent-to-Own can bridge the gap.