The Hidden Cost of Waiting to Buy a Home: The Double Whammy
After a mortgage decline, waiting costs you twice: rent builds zero equity while home prices climb. Here's the math and how to stop both clocks.
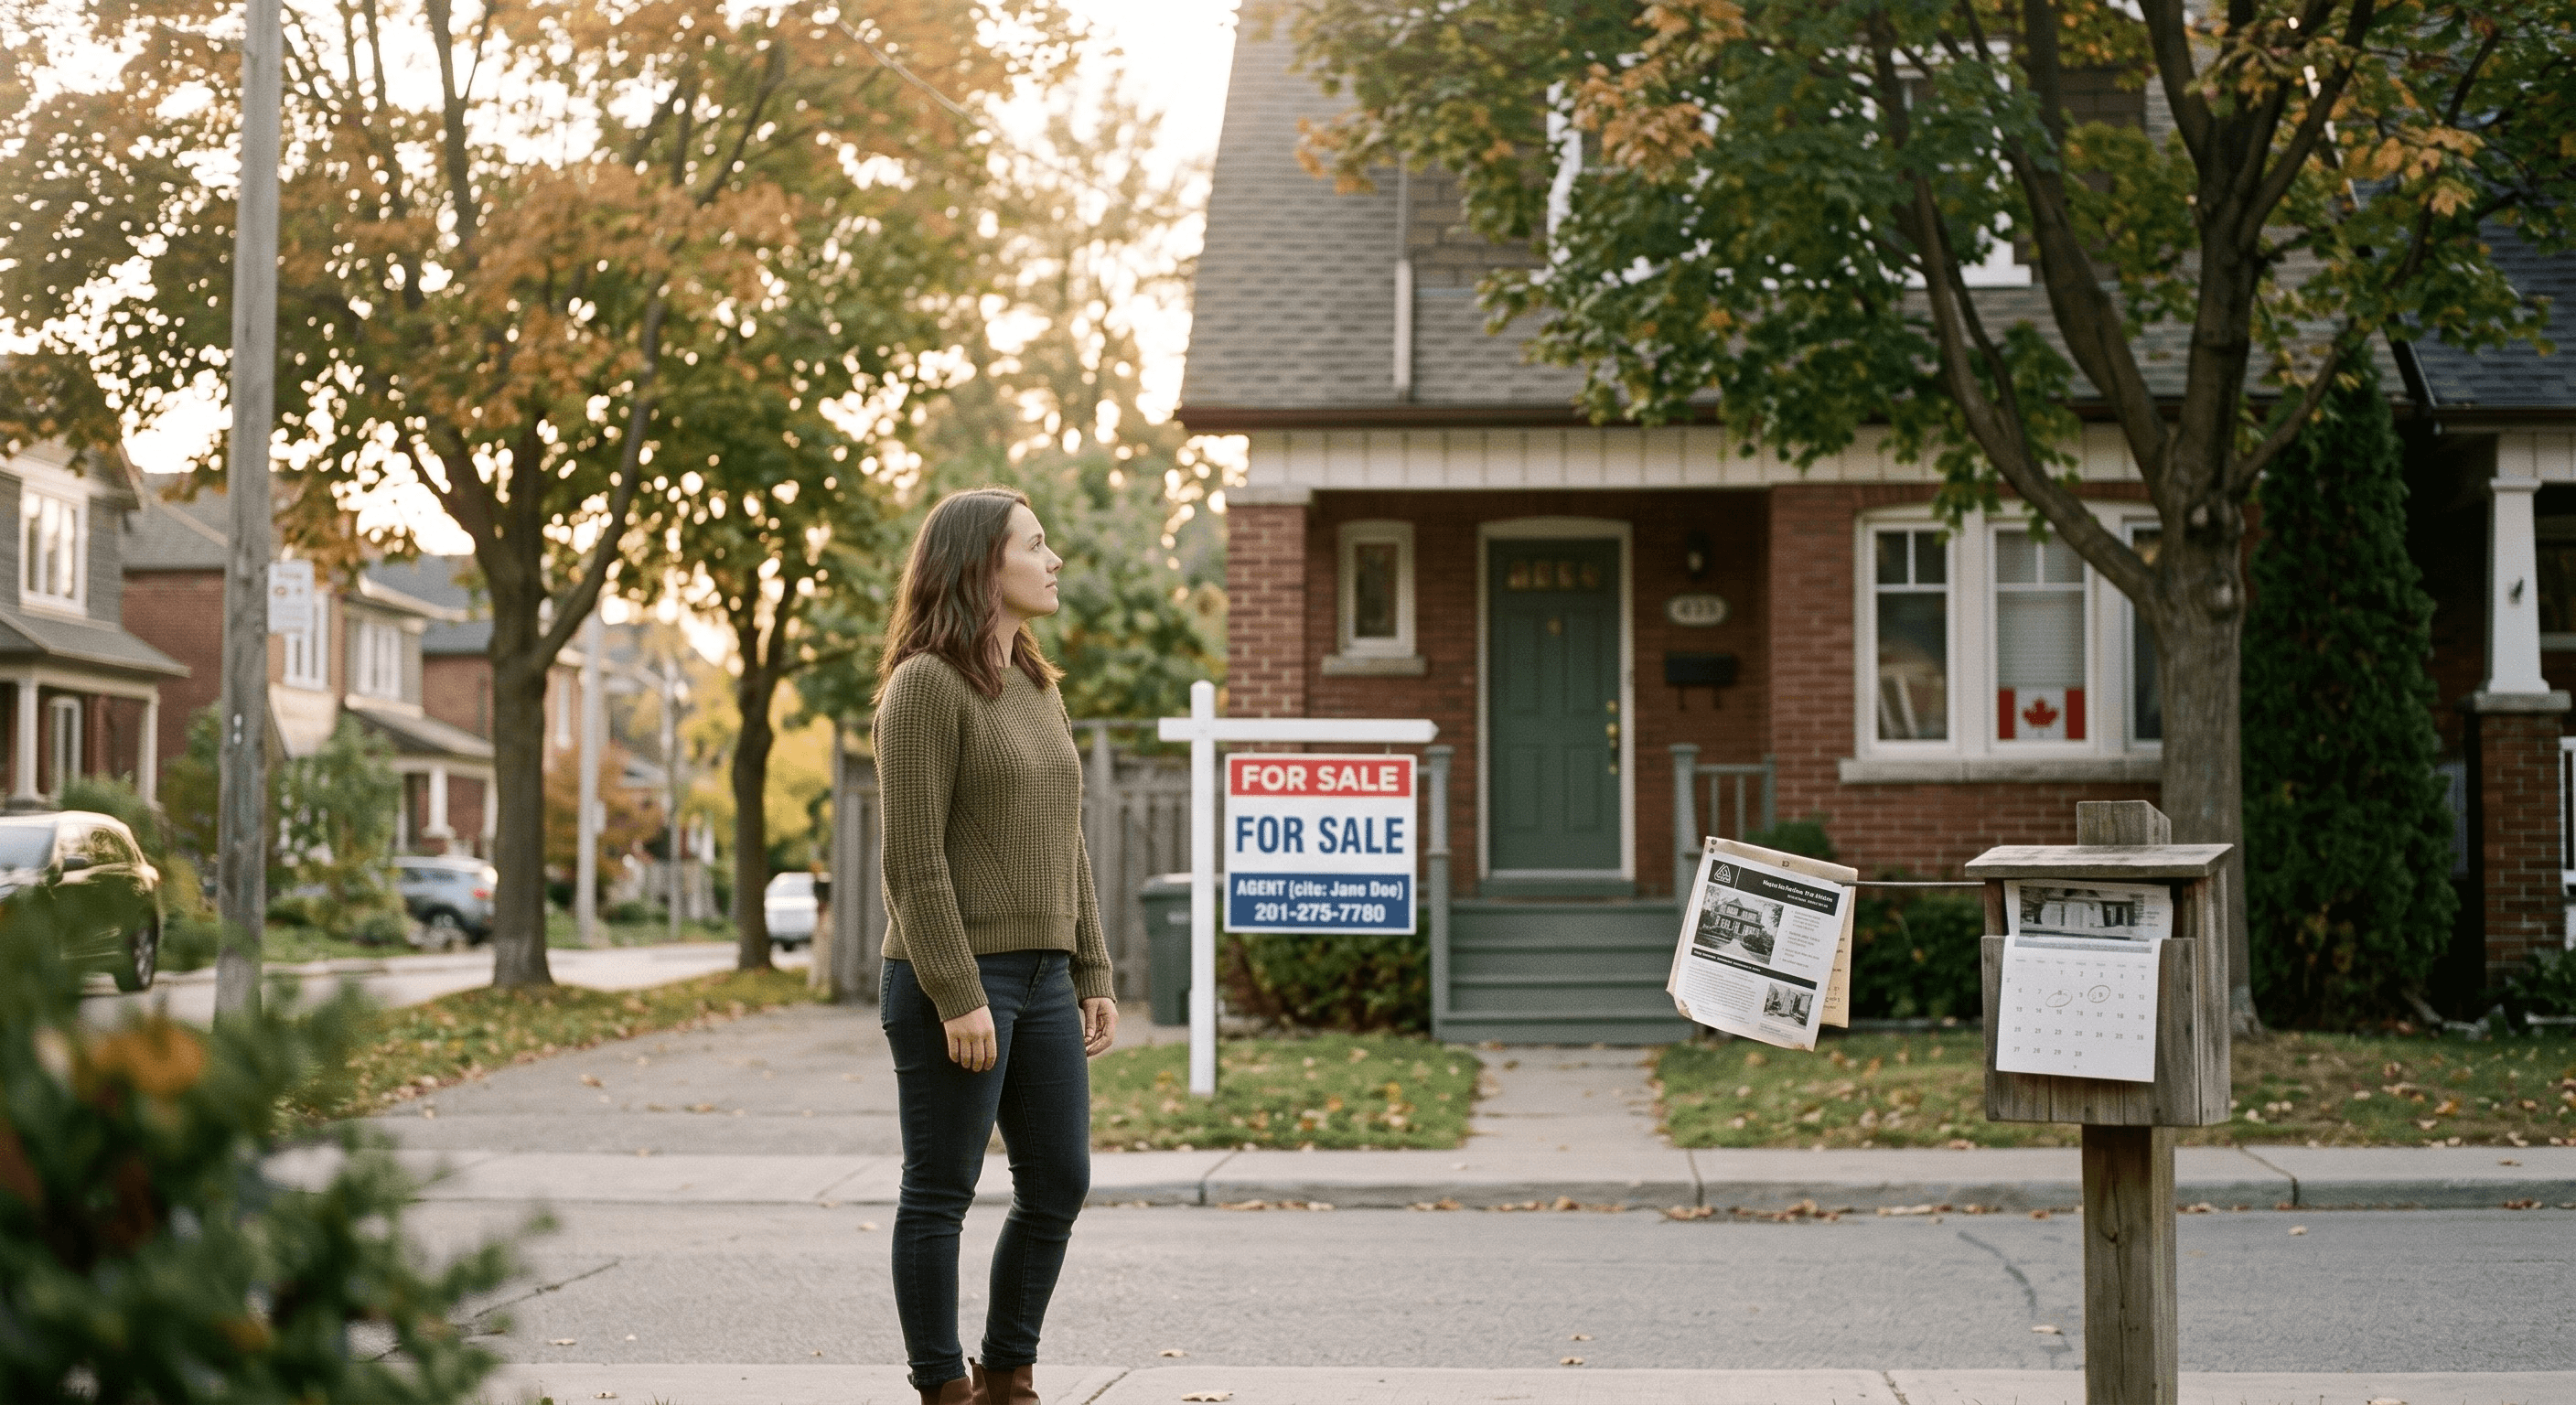
Short answer: After a mortgage decline, renting and waiting to buy costs you twice. First, every month you rent builds zero equity, that money is simply gone. Second, while you wait, home prices usually keep rising, so the home you could afford today quietly drifts out of reach. You're not standing still while you wait; you're falling behind in two directions at once.
The good news: there's a way to stop both clocks. Here's how the math actually works and what to do about it.
The first cost: rent builds zero equity
When you rent, your payment buys one month of shelter and nothing you keep. There's no principal, no equity, no growing asset with your name on it.
Picture three years of renting at $2,400 a month. That's $86,400 paid and $0 in ownership at the end of it. The money always leaves your account. The only question is whether you get anything back for it.
A comparable mortgage payment works differently: a portion goes toward principal, which is ownership you keep. Over those same three years, that's the difference between building nothing and building a real stake.
The second cost: prices keep moving the finish line
Here's the part that quietly hurts the most. While you're waiting to qualify, home prices generally keep climbing and so does the down payment you'll eventually need.
Say you're eyeing a $500,000 home today. At a modest 4% annual appreciation, here's what waiting can look like:
| If you buy... | Approx. price | Higher than today by |
|---|---|---|
| Today | $500,000 | — |
| In 1 year | $520,000 | $20,000 |
| In 2 years | $540,800 | $40,800 |
| In 3 years | $562,400 | $62,400 |
Your "wait two years and try again" plan has a moving finish line. As prices rise, you need a bigger mortgage and a bigger down payment to hit the same home, so the gap you're trying to close gets wider while you save toward it.
Why these two costs compound
Each cost is painful alone. Together, they work against you at the same time.
You're paying rent that builds nothing (cost one) while the home you want gets more expensive (cost two). Two years of "being responsible and waiting" can leave you further from ownership than when you started, not because you did anything wrong, but because both clocks kept running.
> Waiting feels safe. But standing still in a rising market isn't standing still, it's falling behind.
How to stop both clocks at once
The fix isn't to wait faster or save harder against a moving target. It's to get into a home now, on terms that fit your situation, while you become mortgage-ready.
Equity-building homeownership programs (often searched as "rent-to-own") were built for exactly this. Here's how they stop both clocks:
Instead of chasing a target that keeps drifting away, you lock onto it and close the gap from the inside.
What's the difference between this and renting while I wait?
Renting while you wait pays for shelter and exposes you to rising prices with nothing to show for it. An equity-building path puts you in the home now, builds you a stake, and removes the "prices ran away from me" risk. Same waiting period, completely different outcome.
Frequently asked questions
Is it better to buy now or wait for prices to drop?
Timing the market is notoriously hard, and over the long run Canadian home prices have generally trended upward. Waiting carries a real cost, lost equity plus potential price increases, so "wait and see" isn't automatically the safe choice it feels like.
How much does waiting to buy a home actually cost?
Two ways at once: the rent you pay builds zero equity, and price appreciation raises both the purchase price and the down payment you'll need. Even modest 2–5% annual appreciation can add tens of thousands to your target over a couple of years.
Can I buy a home if I was just declined for a mortgage?
Often, yes. Equity-building and rent-to-own programs are designed for buyers who can't qualify today, letting you move in now while you work toward a traditional mortgage.
Learn about the 5 key success factors for rent-to-own.
What's the biggest risk in rent-to-own? Might not be what you think it is.
Tired of falling behind in two directions? Let's stop both clocks and map a path into a home now. Start on our pre-qualification page — it takes minutes and costs nothing.
Related Articles
You're Closer to Owning Than You Think
Most Canadians overestimate how far they are from homeownership. Here's why the gap is smaller and more solvable than you've been told.
What Is Causing the Housing Issues in Canada?
Canada's housing problem is really three problems at once. CMHC data on first-time buyers, stressed mortgage holders and seniors shows why.
Rent-to-Own vs Renting and Saving: Which Path to Homeownership Is Right for You?
Choosing between a rent-to-own agreement and traditional renting while saving for a down payment can significantly impact your path to homeownership. This comprehensive guide breaks down both options to help you make an informed decision.