You Can Qualify for Rent-to-Own With a Credit Score as Low as 500!
Rethink Renting accepts credit scores as low as 500. Here's why the bank's 680 wall doesn't apply — and the five things to fix during your term.
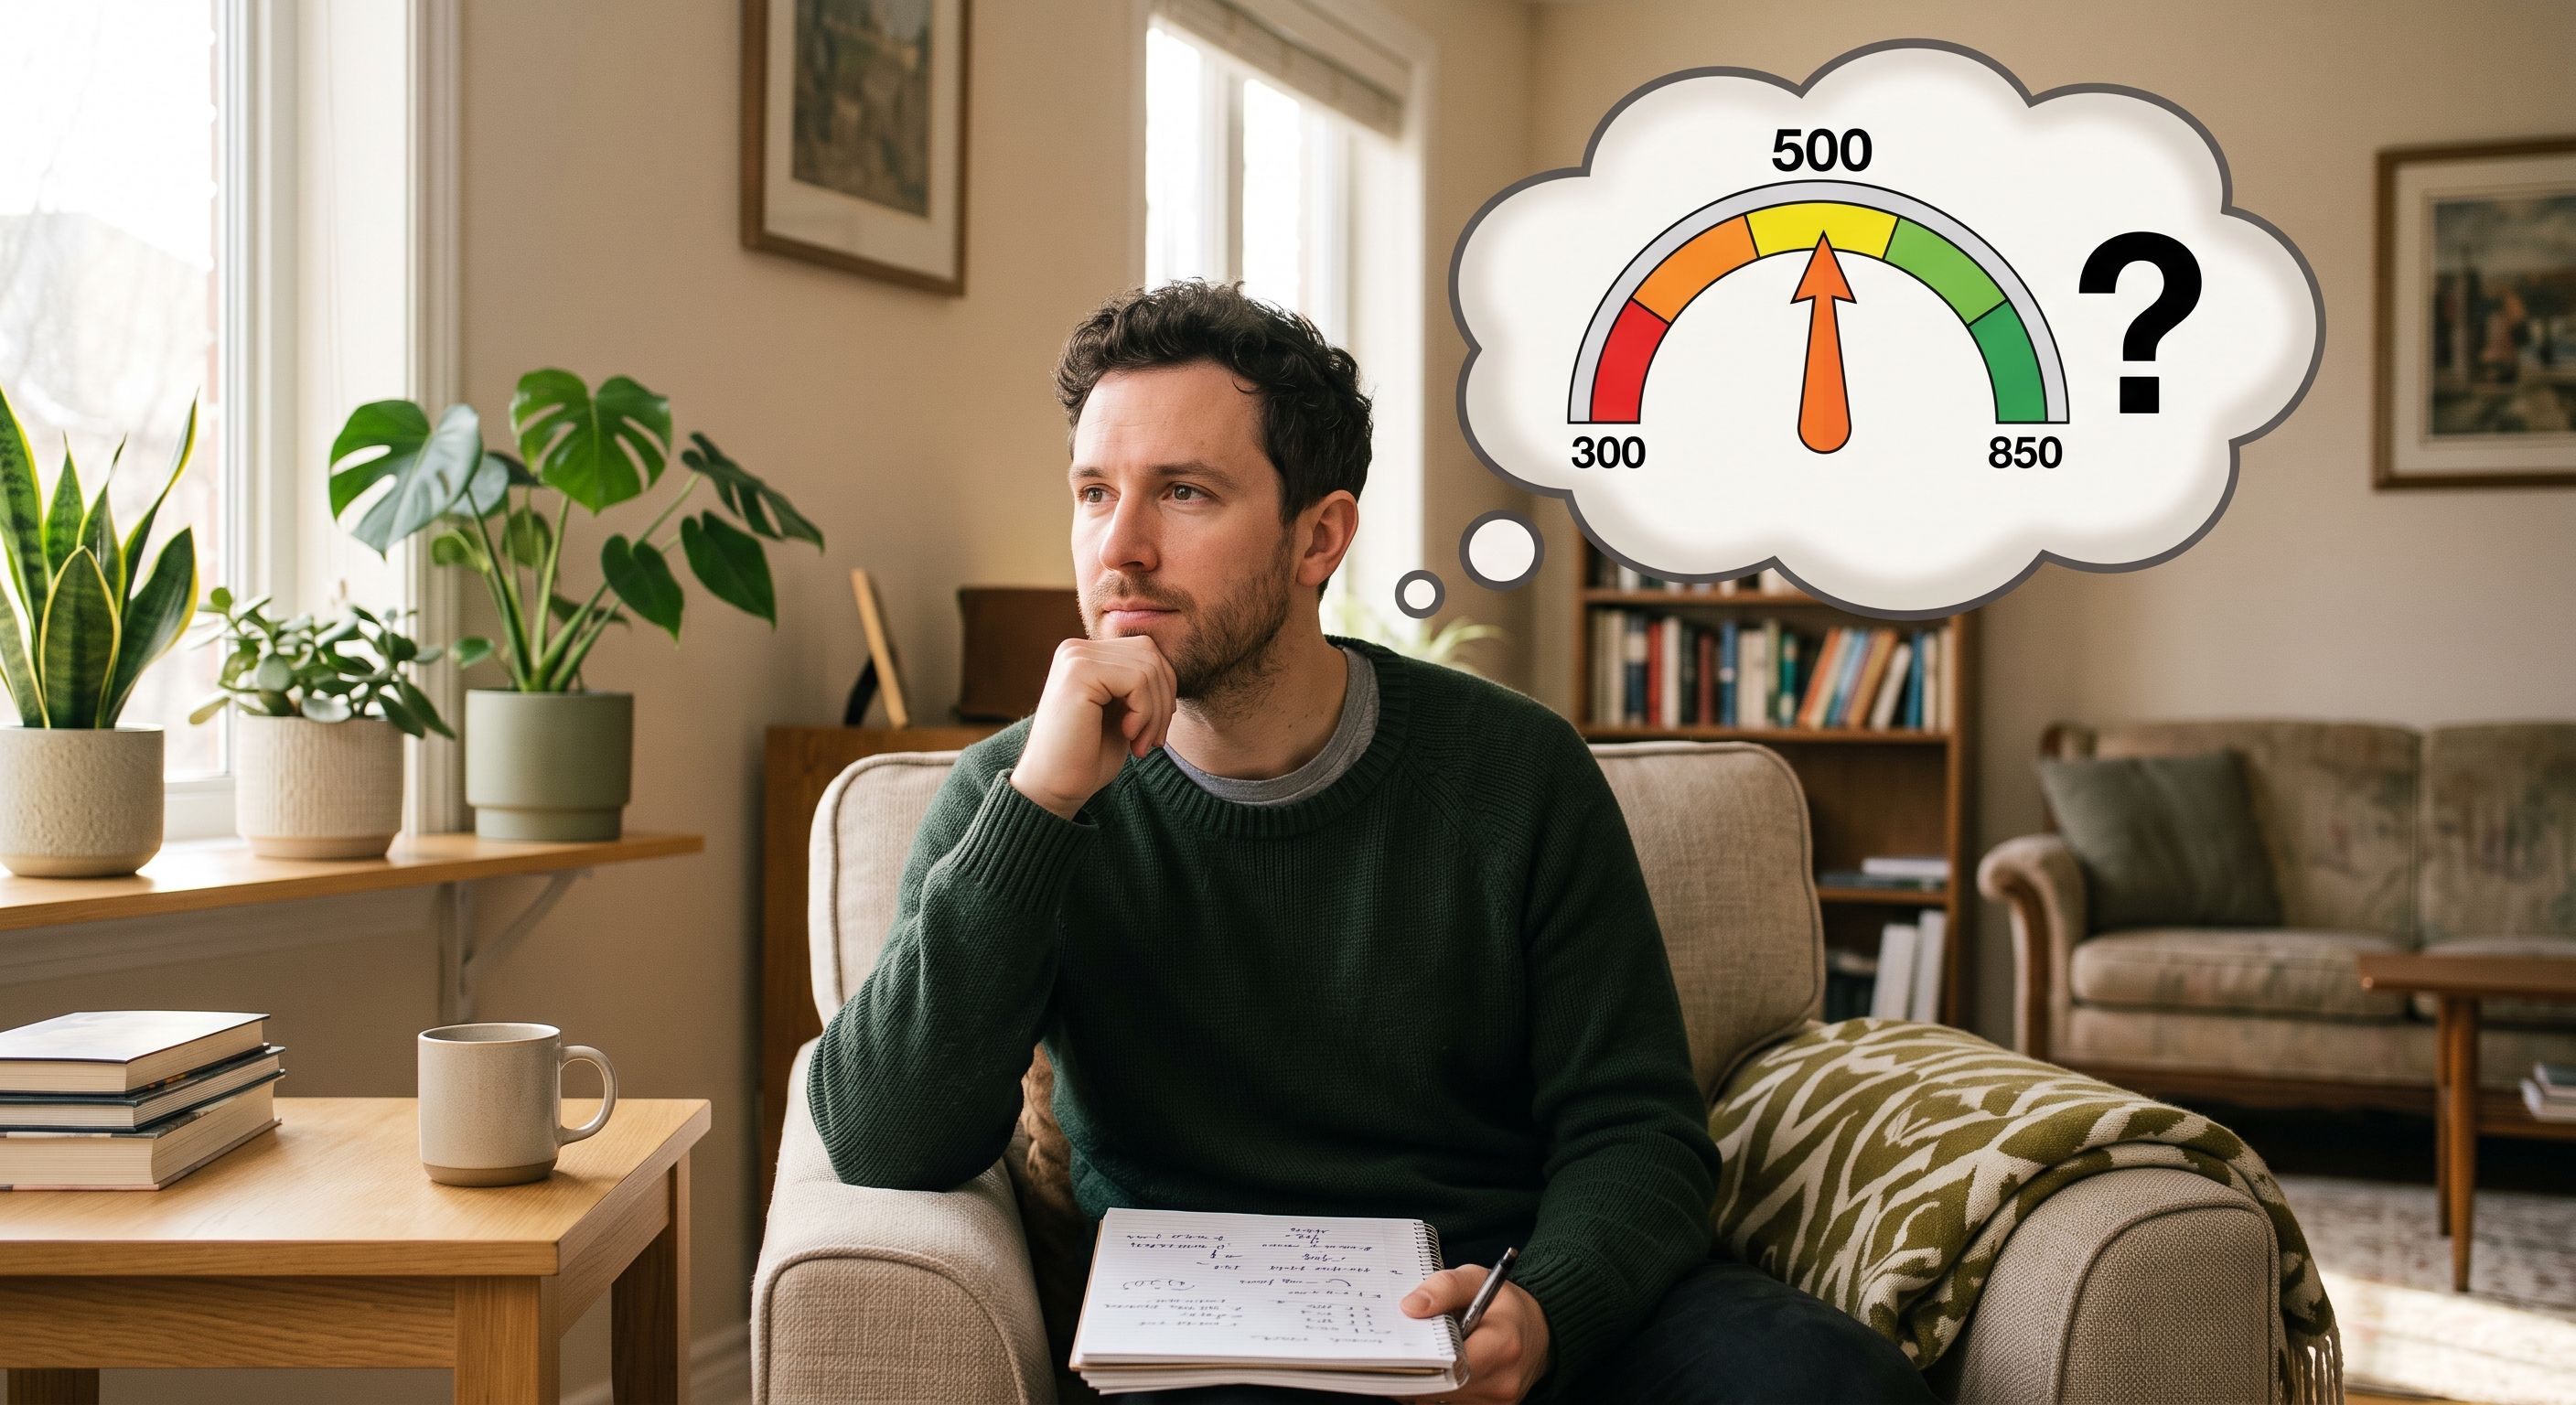
> Quick answer: Rethink Renting accepts applicants with credit scores as low as 500 but it is a case-by-case scenario. A 500 score sits far below what any bank will fund, but it is not what decides your application: your income, your job stability, and whether the problems on your credit file are fixable inside a two-to-four-year term are what decide it. The program is built to give you that time, not to skip the credit conversation.
Why 500 works here when it doesn't work at a bank
If you have applied for a mortgage recently, you already know where the wall is. Canada's A-lenders, the major banks, credit unions, and monoline lenders, typically want a minimum of 680 for an uninsured mortgage, and 720 or higher unlocks the most competitive rates. Insured mortgages generally require at least 600 for one borrower, and scores between 550 and 680 get routed to alternative or "B" lenders at higher rates. Below that, you are looking at private money and a much larger down payment plus 1-2% in fees.
At 500, you are not near any of those doors.
Ownable/Clover Properties is not underwriting a mortgage today. A private investor family purchases the home you choose; you occupy it under a lease plus an option agreement that locks your timeline, your terms, and your equity-sharing split. Your maximum home price is set by a formula, annual income × 4.5, plus your option deposit of 4–5% of the home value, inside a $400,000–$900,000 range across Southwestern Ontario and Alberta.
One caution: if a rent-to-own company tells you credit does not matter at all, leave. Credit matters. It just doesn't have to be fixed before you move in.
How much time does the program term actually give you?
The term runs two to four years, with an optional one-year extension. That is not an arbitrary window, it is roughly what a 500-score rebuild takes. Moving from around 500 into the fair range of 580–669 generally takes 12 to 18 months of responsible credit use. Getting from 500 to 700 typically takes two to three years with consistent effort, no new negative marks, and active use of a secured credit card.
That is the whole design. You are living in the home while the clock that matters is running.
What are the 5 things to do during the term?
Your score is a compressed version of five factors: payment history (35%), utilization (30%), length of history (15%), credit mix (10%), and new inquiries (10%). Payment history and utilization alone account for 65%, so most of the real work is paying on time and keeping balances low. Everything below follows from that.
When is a 500 score not enough?
We would rather say this now than after you have gone through the application process:
Rent-to-own is a bridge to a conventional mortgage. If you use the term the way it is designed to be used, you exit as a homeowner with a bank behind you. If you don't, you exit having forfeited your option deposit. Both outcomes are entirely in your hands, and we will tell you which one we think is likely before you sign.
This article is educational and is not financial, legal, or mortgage advice. Program terms are subject to approval and may vary by property and jurisdiction.
Want to book a call to discuss your situation and see if we can help your family? Click here.
Related Articles
How Does Rent-to-Own Work in Ontario? A Plain-Language Guide
Learn how rent-to-own works in Ontario, step by step: the 5% option deposit, monthly payments, term length, red flags, and how you buy the home.
How to Rebuild Your Credit to Qualify for a Mortgage
Declined for a mortgage? Here are the ten steps to rebuild your credit, what score A-lenders want to see, and how long it really takes.
Rent-to-Own Success Tips: What Families Who Actually Buy Do Differently
Rent-to-own works when it's built around one goal: mortgage approval. Here's what the families who actually close do differently, from day one.