From Renting to Owning: Michael and Danielle's Three-Year Journey
A family unable to qualify for a mortgage stayed in their home and became owners by using rent-to-own to build the credit and financial profile their lender required.
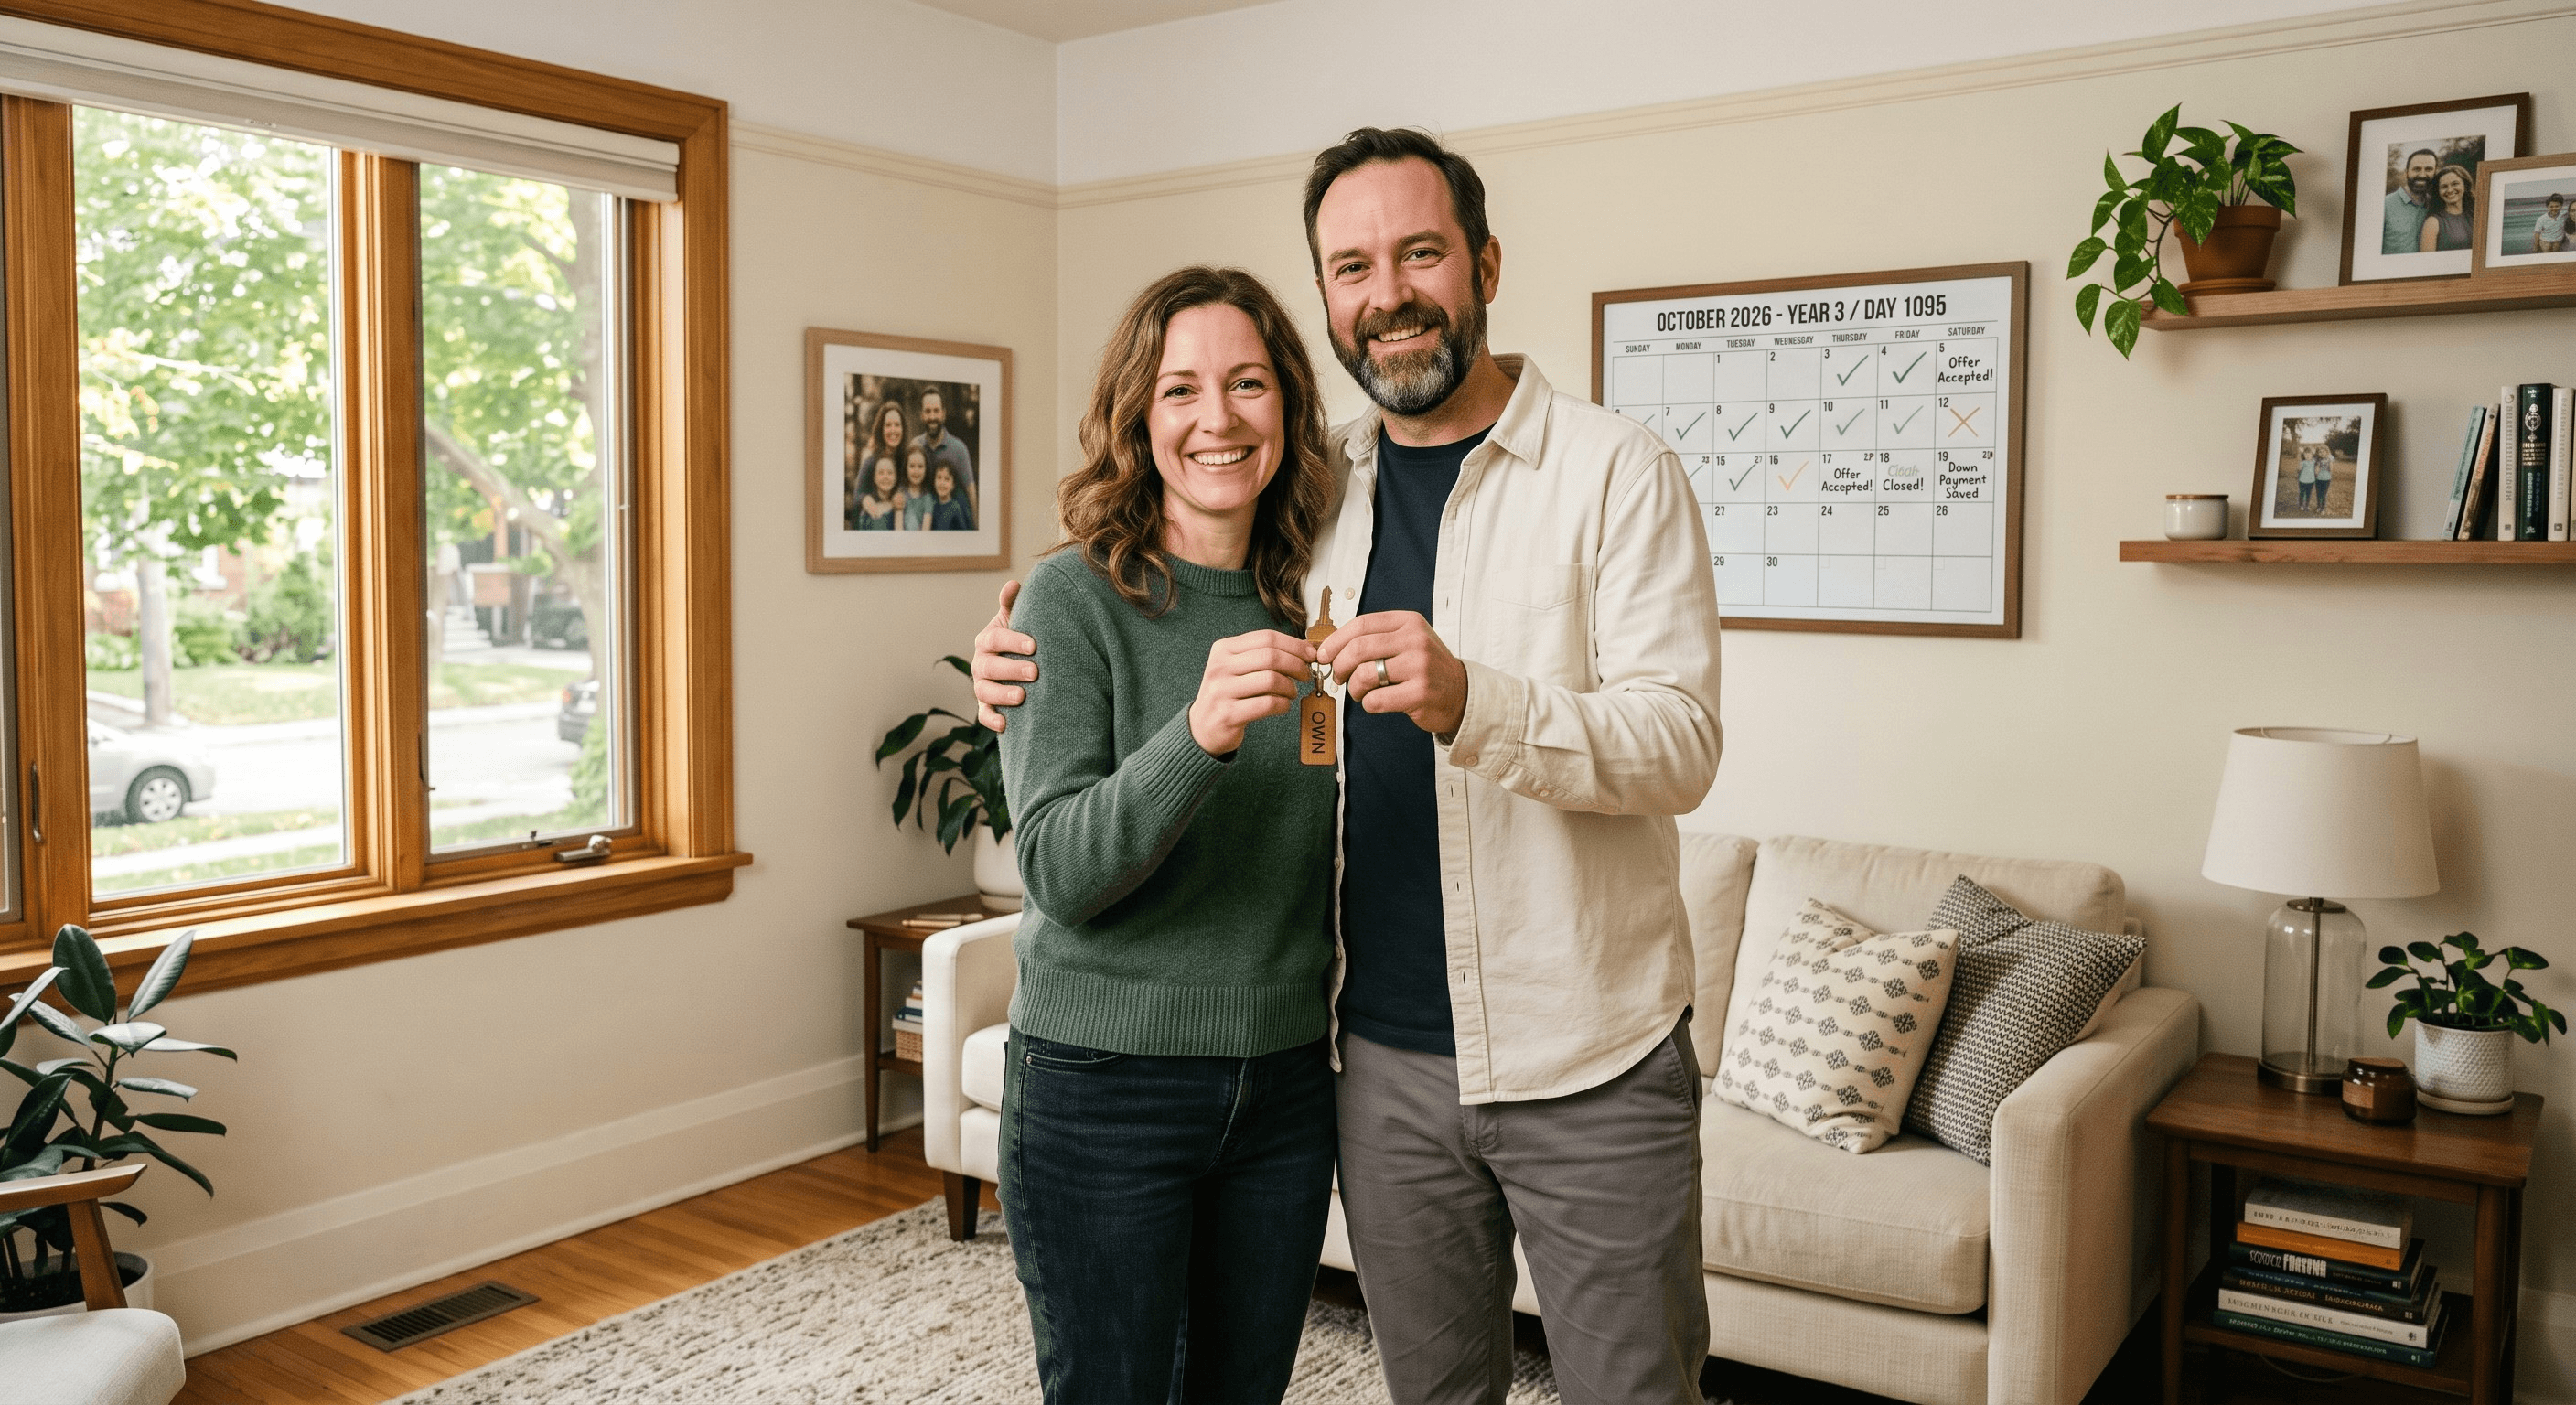
Why Didn't Michael and Danielle Qualify for a Mortgage?
For years, Michael and Danielle had rented the same family home. Their landlord announced a sale, and they wanted to but but when they approached the bank, the bank said no.
Their income was stable. The real barriers were credit repair and debt ratios. A car loan was pushing their debt-service numbers outside the lender's stress-test guidelines. A bank doesn't care that you can afford the payment; they care whether your credit score, existing debt load, and income ratio meet the formula. Michael and Danielle didn't.
Mortgage decline feels permanent until you understand what it actually means: not now not never.
What Were Their Options: Continue Renting or Find a Real Bridge?
The family faced a choice that tens of thousands of Canadians face every year. Stay and look for an alternative, or move and start over somewhere else.
Moving meant leaving the neighborhood their children knew, the schools they attended, and the community they'd built. It meant paying rent again, building zero equity, while hoping their credit improved on its own. That's not a plan; that's waiting.
They did what the best buyers do: they researched alternatives to traditional mortgage financing. They found Clover Properties.
How Did Rent-to-Own Make This Possible?
Clover Properties worked with Michael and Danielle to structure a three-year pathway to ownership. Here's how it worked:
The Setup: A private investor family purchased the home from their landlord and entered into a rent-to-own agreement with Michael and Danielle. The family stayed in the home they already loved. Michael and Danielle paid a monthly housing payment calibrated to qualify them for a future mortgage, not just cover the investor's costs.
The Timeline: Three years to repair credit, pay down the car loan, and demonstrate the debt-service ratio the bank needed to see.
The Equity Share: Every month, a portion of their housing payment was credited toward equity in the home, real ownership stake, locked into the option agreement, fully transferable when the mortgage closed.
The End Goal: Become mortgage-ready and purchase the home outright.
What Did Michael and Danielle Actually Do Over Three Years?
They didn't sit and hope. They executed a financial plan.
The result: a financial profile that looked fundamentally different from the one the bank had rejected three years earlier.
What Happened When They Returned to the Bank?
At year three, Michael and Danielle reapplied. This time, the file was approved.
Their credit had improved. The car loan was mostly paid off. Their debt ratios now fit the lender's criteria. They qualified for a conventional mortgage, completed the purchase, and became the legal owners of the home they had once rented.
The transition was not forced. It was intentional.
What Makes This Outcome Possible for Others?
A mortgage decline does not mean a family cannot afford to own. Often, it means they need:
Rent-to-own, when structured correctly, provides all five.
The Bigger Picture
What could have been another forced move became a successful transition into homeownership. The landlord sold the property. The investor family provided the bridge. Michael and Danielle kept their home and their community while preparing for the mortgage they could not qualify for at the beginning.
A mortgage decline is not the end of the story. Sometimes, it's the beginning of the plan.
5 Ways Rent-to-Own is like homeownership in training. Read it here.
Can you get a mortgage while in a consumer proposal?
Ready to find your path to homeownership? Discover whether you qualify for Clover Properties' rent-to-own program with our pre-qualification assessment.
Related Articles
You Have the Income, so Why Won't the Bank Approve Your Mortgage?
Strong income. Down payment saved. Still declined by the bank? Learn why mortgage approvals fail and how we help Canadians get into homeownership.
The Consumer Proposal Timing Trap: Why Your Rent-to-Own Term Shouldn't End When Your Proposal Does
Most A-lenders want 12 to 24 months of clean credit after your consumer proposal is discharged. If your rent-to-own term ends the same year, you have no runway and your option deposit is what's at risk.
Private Mortgage vs Rent-to-Own: The Safer, Cheaper Path to Homeownership
Not all mortgage alternatives are equal. Here's the hard truth about some private lenders—and why rent-to-own may be the smarter, safer path to owning your home.