More Homes, More Power: What Elevated Inventory Means for Buyers Who Aren't Quite Ready Yet
Housing inventory sits 49% above the 10-year March average — and that shifts negotiating power to buyers. Here's how to use this market window if you're not mortgage-ready yet.
If you've been watching the housing market from the sidelines, here's something worth knowing: the playing field has shifted and it's shifted in your favour.
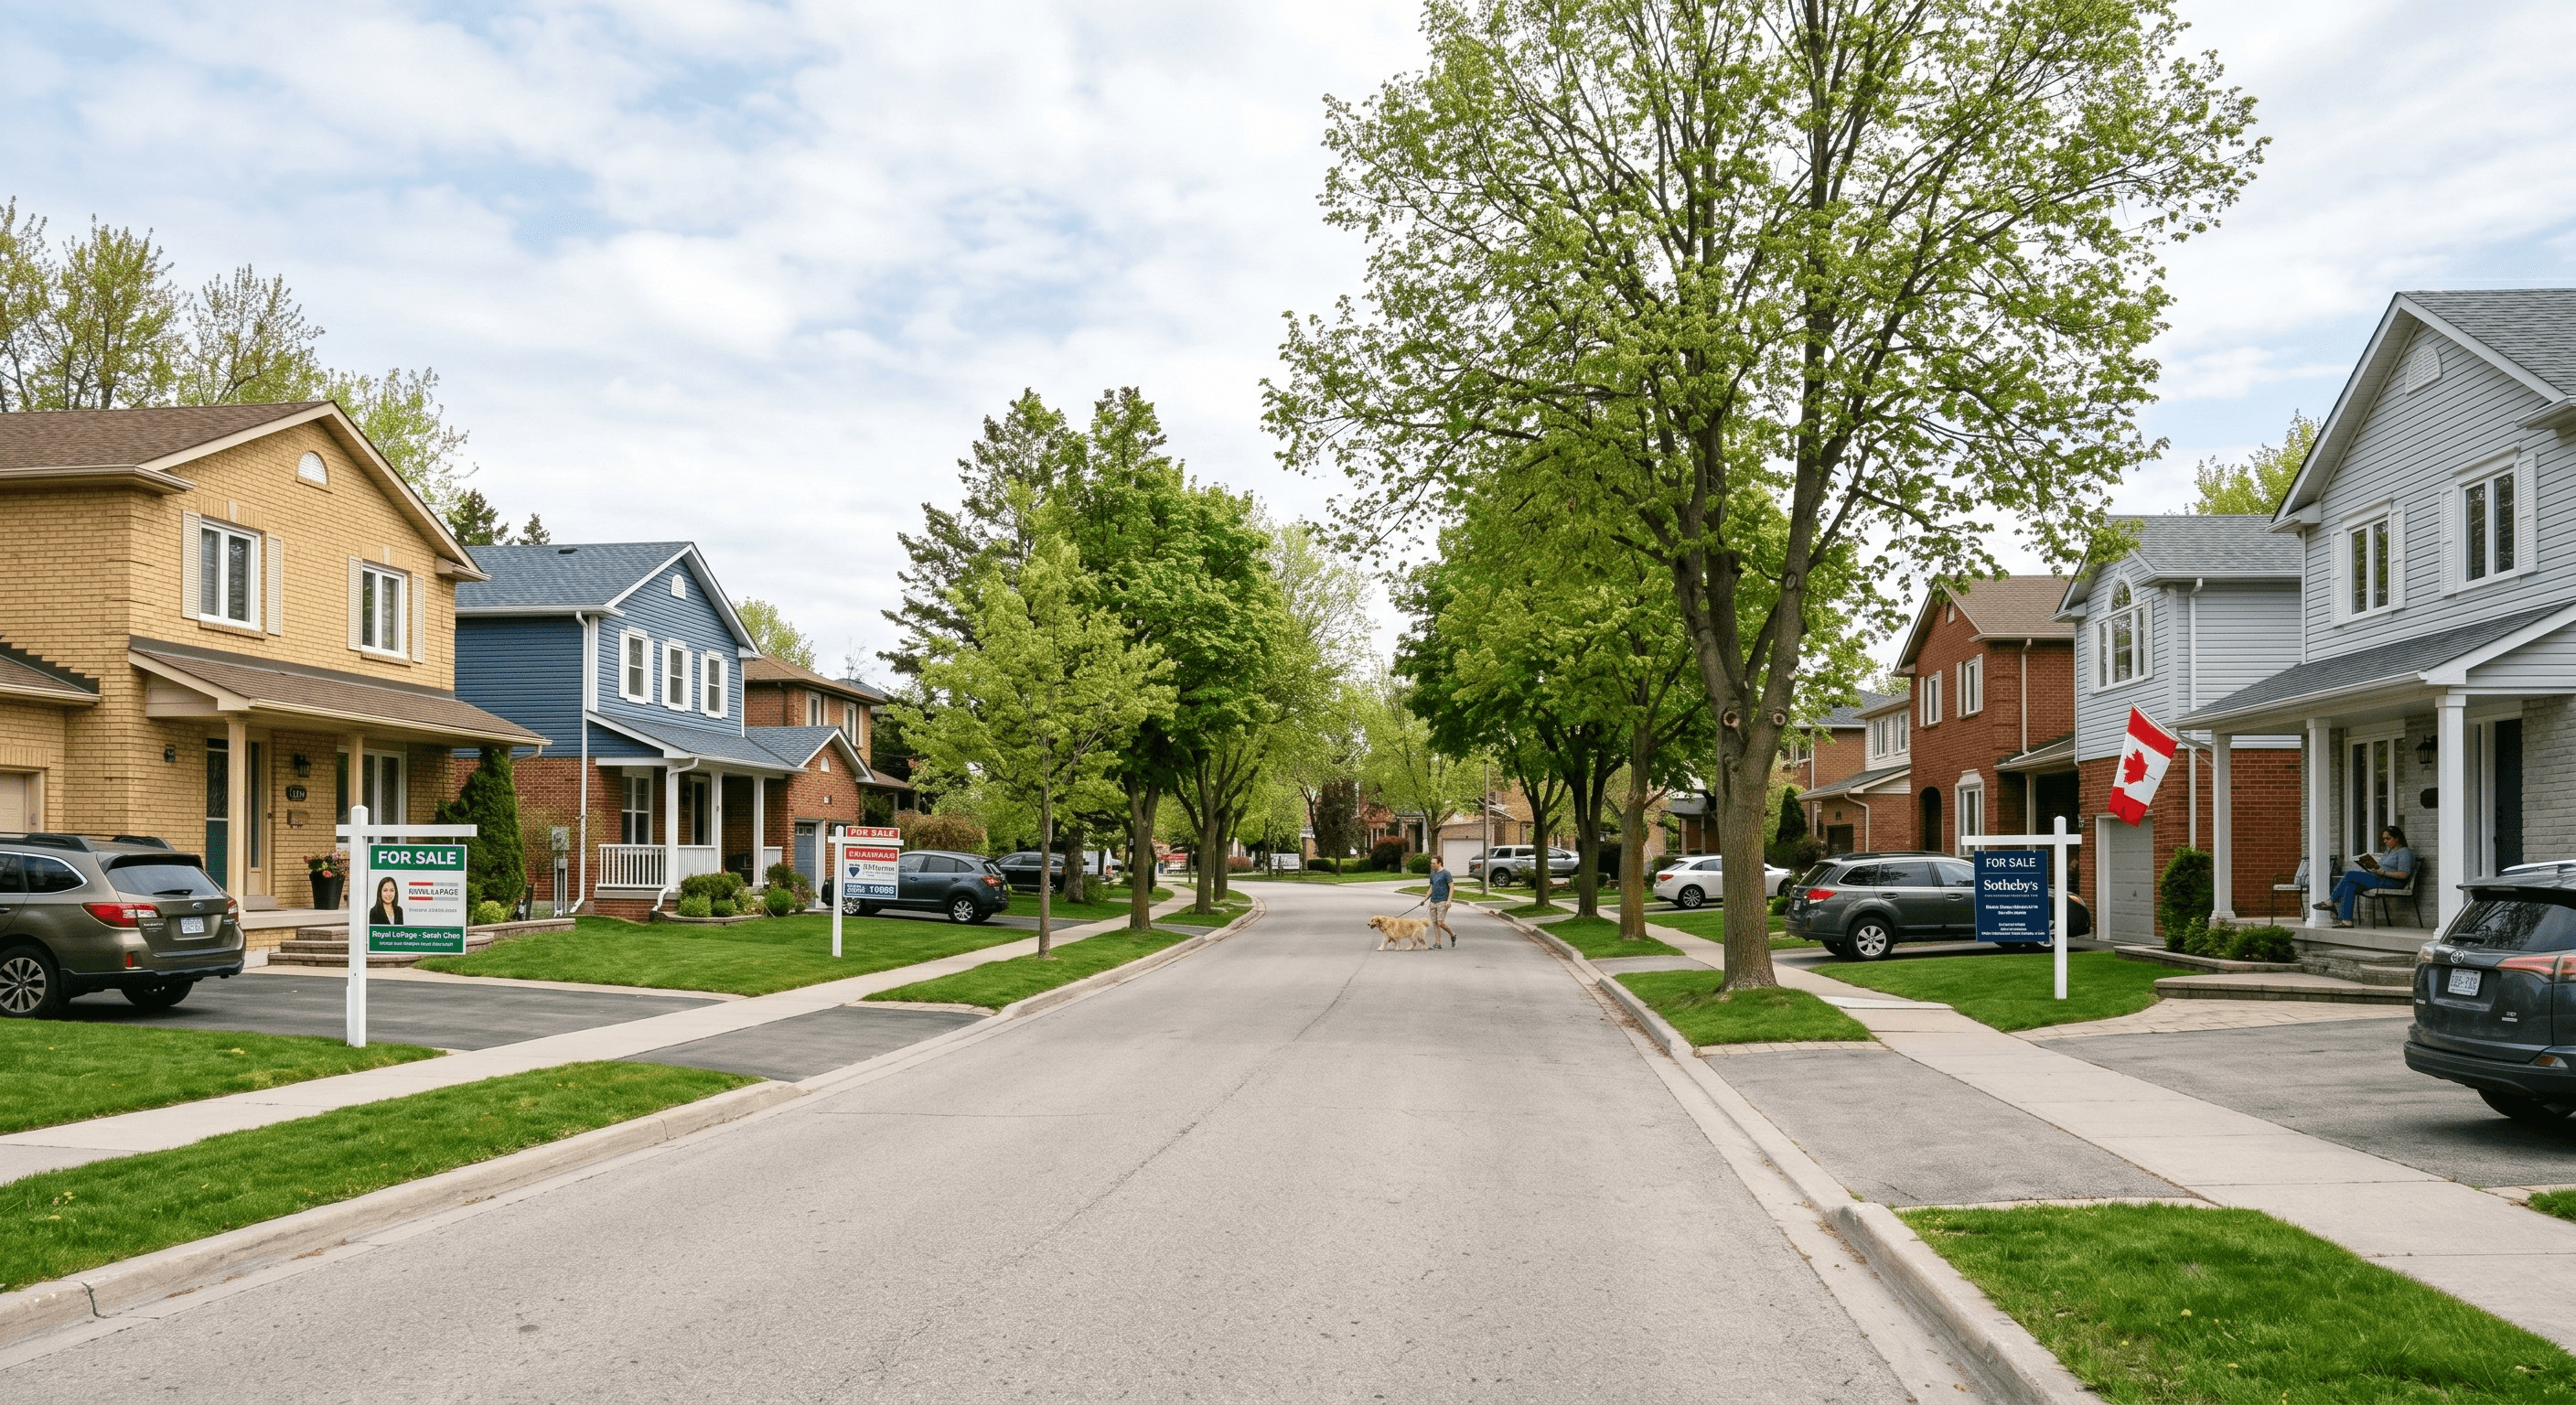
As of March 2025, housing inventory across Canada sits roughly 49% above the 10-year March average. That's not a small blip. That's a structural shift in market conditions that changes how homes are priced, how long they sit, and how much room buyers have to negotiate.
The question is: are you positioned to take advantage of it?
What "Elevated Inventory" Actually Means
When inventory is low, like it was during the frenzied 2021–2022 market, sellers held all the cards. Homes sell in days. Buyers waive conditions. Offers come in at 10%, 15%, even 20% over asking.
When inventory is elevated, the dynamic flips. More homes competing for fewer buyers means:
In short: buyers get to be buyers again, not contestants in a bidding war.
The Catch: You Still Have to Qualify
Here's where many people get stuck.
The market opportunity is real. But your ability to act on it depends entirely on whether a lender will approve you and right now, that bar is higher than it looks.
The mortgage stress test (OSFI Guideline B-20) requires you to qualify at either your contract rate plus 2%, or 5.25%, whichever is higher. For most buyers, that gap between what you can afford and what a lender says you qualify for is significant.
If you've had credit challenges, are new to Canada, or are still building your down payment, that gap doesn't close by watching listings. It closes by working the problem, systematically, over time, with a plan.
Why This Market Moment Actually Favours Rent-to-Own
Most people assume rent-to-own is a last resort for desperate buyers. That's the old story. Here's the new one:
In a buyer's market, rent-to-own lets you lock in today's conditions before the market turns. And it will. History has shown this to be the case.
When you enter the Clover Properties program, your purchase price is set at the beginning of your term. You're not watching the market from the outside hoping inventory stays high. You've already secured the home, locked in the price conditions, and started building equity through monthly credits. At the same time, you are using the term to do exactly what lenders need to see: stable income documentation, improved credit, and a growing down payment.
Meanwhile, the elevated inventory means there are more homes to choose from in the $400,000–$900,000 range across Southwestern Ontario and Alberta. More options. Less pressure. More time to find the right fit, not just any available property. And this is a key consideration. You must "love" where you live to succeed.
Three Types of Buyers Who Should Be Paying Attention Right Now
Rebuilders — If you're post-bankruptcy or post-consumer proposal, your credit needs runway. Two to four years of on-time payments, active tradelines, and a clean file can get you from declined to approved. The market won't wait for you to be ready. A rent-to-own program lets you start now.
Newcomers — Canadian credit history takes time to build. A T4 from a new employer, a secured credit card, Permanent Residency and consistent payment behaviour across 24–36 months puts you in a completely different position with A-lenders. Lock in the home today; qualify for the mortgage on your own terms.
Savers — The stress test means the goalposts keep moving as prices shift. A rising market punishes savers who wait: every month your down payment grows, the purchase price you need to qualify for grows too. Option credits and a fixed purchase price solve this problem in a way that a savings account simply can't.
The Window Won't Stay Open Indefinitely
Elevated inventory is a market condition, not a permanent state. When rate cuts gain traction and buyer confidence returns, that inventory gets absorbed. The homes that are sitting today start moving. Negotiating power shifts back toward sellers.
The buyers who benefit most from this moment are the ones who use it: not to wait and watch, but to get into a position where they can act when their qualification timeline catches up.
If you're 12, 24, or 36 months away from mortgage-ready, that timeline starts today.
Why now is a good time to buy in Ontario.
Is now a good time to buy in Alberta?
When is Rent-to-Own a good idea?
Ready to find out if you qualify? Check it out on our pre-qualification page and we'll walk through your situation together.
Related Articles
You're Closer to Owning Than You Think
Most Canadians overestimate how far they are from homeownership. Here's why the gap is smaller and more solvable than you've been told.
What Is Causing the Housing Issues in Canada?
Canada's housing problem is really three problems at once. CMHC data on first-time buyers, stressed mortgage holders and seniors shows why.
Rent-to-Own vs Renting and Saving: Which Path to Homeownership Is Right for You?
Choosing between a rent-to-own agreement and traditional renting while saving for a down payment can significantly impact your path to homeownership. This comprehensive guide breaks down both options to help you make an informed decision.