Why Was I Declined for a Mortgage? 3 Real Reasons (and What to Do)
Declined for a mortgage in Canada? The real reason is usually one of these three things, credit, a thin newcomer file, or self-employed income. Here's each fix.
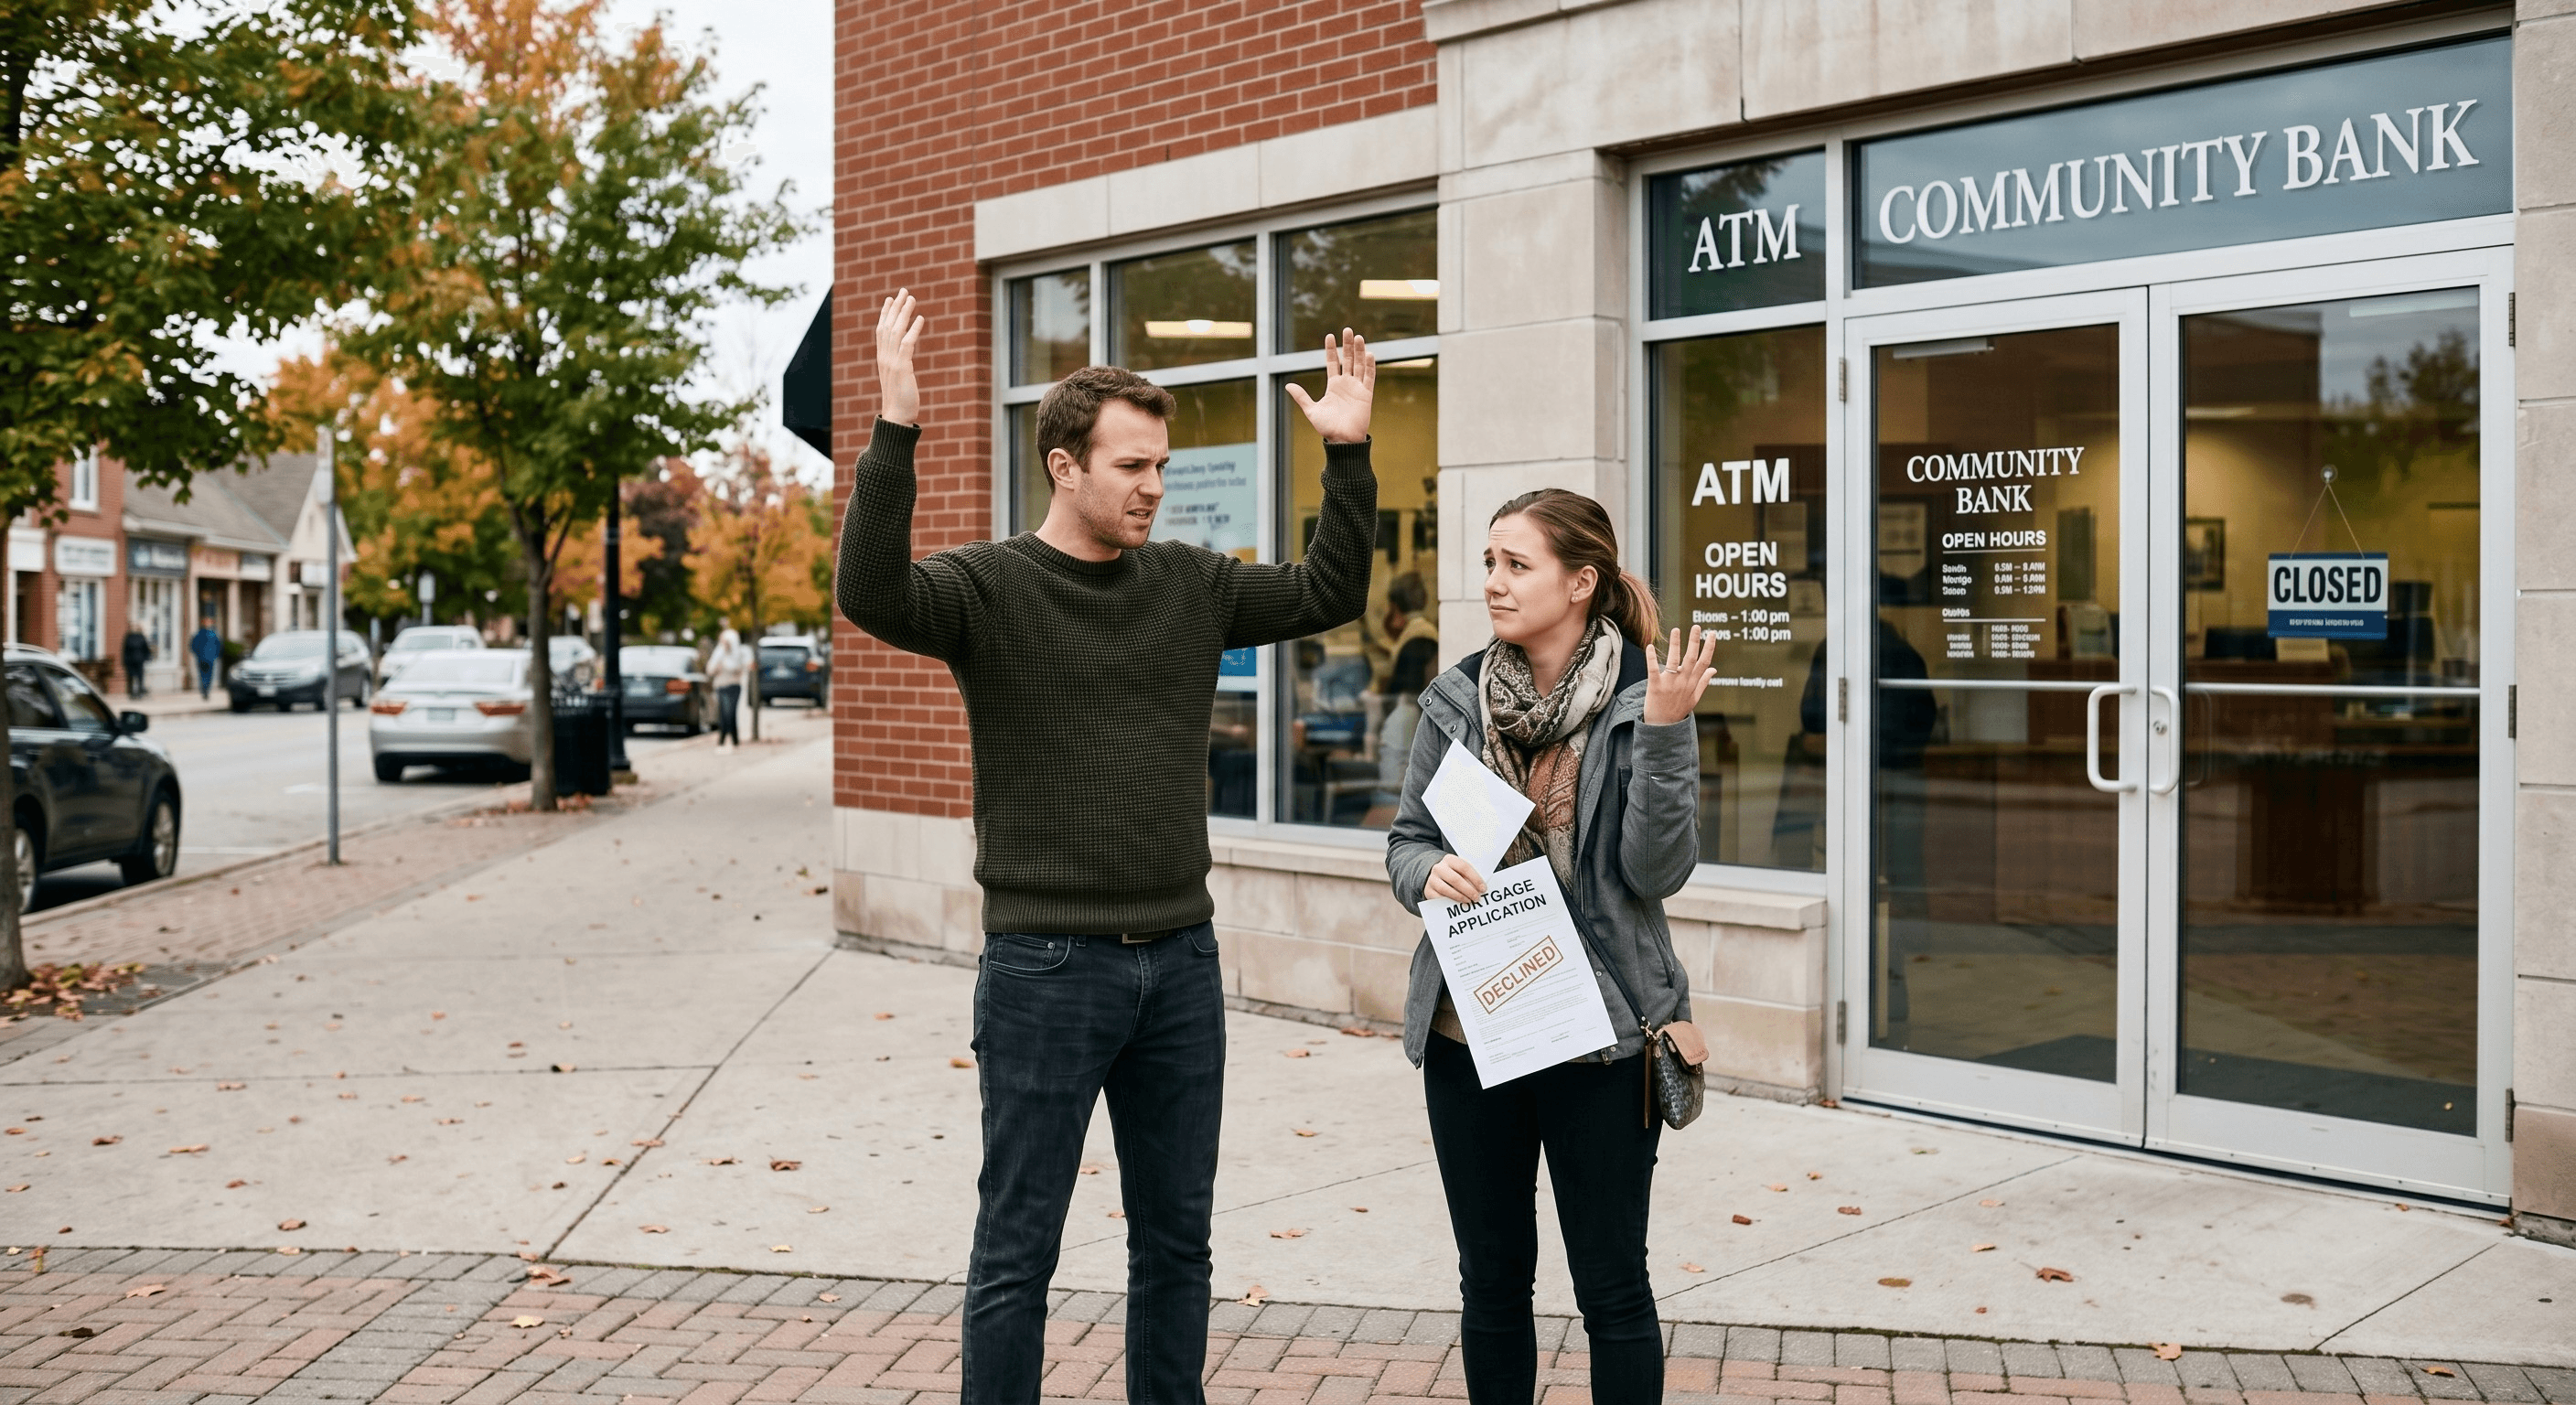
Short answer: Most Canadians declined for a mortgage are turned down for one of three reasons: a credit score that hasn't caught up after a rough patch, a "thin" file as a newcomer with little Canadian credit history, or self-employment income that looks smaller on paper than it really is. There are other reasons too, of course like not having enough for a down payment or closing costs. But none of these mean you can't own a home, and each one has a clear path forward the bank rarely mentions.
You probably never got a straight answer for why you were declined. Here's what was likely going on behind the scenes and what to do about it.
Reason 1: Your credit took a hit during a rough patch
A job loss, a medical event, a divorce, a stretch of missed payments. Life happens, and your credit score wears the bruise long after you've recovered.
The problem is timing. A credit score is backward-looking. It reflects what happened, not the disciplined months you've put together since. So you can be in a completely stable position today and still be judged on a dip from two years ago.
The path forward: Credit is easy enough to rebuild, it just takes effort and time. Pay every bill on time, keep credit card balances below about 30% of their limits, and avoid opening or closing accounts right before applying. Many people move from "declined" to "qualified" in 12 to 24 months. The mistake is waiting in a rental during those months instead of building toward ownership at the same time, more on that below.
Reason 2: You're a newcomer with a "thin" credit file
If you're new to Canada, you may have strong income, real savings, and a spotless financial history in another country. Canadian lenders often can't see any of it.
To their system, no Canadian credit history means a "thin file," and a thin file reads as risk even when you're one of the safest borrowers they'll ever see. It's not a judgment of you; it's a gap in what their model can measure.
The path forward: Start building Canadian credit immediately. A secured credit card, a small reported utility or phone account, and on-time payments all create the track record lenders need. Some newcomer mortgage programs and alternative lenders also look beyond the thin file. In the meantime, equity-building homeownership programs are especially common for newcomers, because they let you get into a home while your Canadian credit history grows.
Reason 3: You're self-employed and your income looks lower than it is
This one is almost unfair. Business owners, freelancers, and contractors often earn plenty but they write off expenses to run their business, which lowers the net income that shows on their tax returns.
Lenders qualify you on that lower reported number, not on what you actually take home. So a thriving self-employed person can look, on paper, like they earn far too little to carry a mortgage.
The path forward: Time and documentation fix most of this. Two or more years of consistent self-employment, clean financial statements, and a mortgage broker who specializes in self-employed clients can change the picture significantly. Some lenders use "stated income" or alternative documentation programs built for exactly this situation. And again, you don't have to sit on the sidelines while you assemble that paper trail.
Why didn't the bank just explain this?
Because a bank's system isn't built to find a way to yes. It's built to protect the bank. When your file doesn't fit a fixed box with the bank like credit score, debt-service ratios, documented income, the answer is no, and the person across the desk often isn't able to do more than relay it.
> A "no" from that system is a comment on the bank. It is not a verdict on you.
The option none of these reasons rules out
Here's what ties all three together: every one of them is temporary, and every one of them is fixable with time. The danger isn't the decline, it's spending the next two years paying mortgage-level rent and building zero equity while you wait to requalify.
Equity-building homeownership programs (often searched as "rent-to-own") were created for exactly this gap. You move into a home you choose, pay a monthly amount in the range of a comparable mortgage, and a share of your payment works toward ownership. All of this while you rebuild credit, grow your Canadian history, or document your self-employed income.
Frequently asked questions
What are the most common reasons mortgages get declined in Canada?
The big three are a low or recovering credit score, insufficient Canadian credit history (common for newcomers), and self-employment income that's understated on tax returns. Debt-service ratios that are too high, or not having enough for a down payment and closing costs, are other frequent causes.
How long does it take to recover from a mortgage decline?
It depends on the reason. A documentation issue can be fixed in months, while rebuilding credit or Canadian history typically takes one to two years.
Can self-employed people get a mortgage in Canada?
Yes. With two-plus years of records, clean statements, and the right lender or broker, self-employed borrowers qualify regularly, sometimes through alternative-documentation programs.
Not sure which reason was yours? Book a zoom call with me and I will be happy to discuss the option that impacted your mortgage approval and see if we can help you get on the path to homeownership today.
Related Articles
Rent-to-Own Success Tips: What Families Who Actually Buy Do Differently
Rent-to-own works when it's built around one goal: mortgage approval. Here's what the families who actually close do differently, from day one.
5 Actions to Take After Starting a Rent-to-Own
Signed a rent-to-own agreement? Five things to do now, paperwork, maintenance, a real budget, a repair fund, and credit repair that actually works.
What You Should Know Before You Start Shopping for a Home in Canada
Six things to settle before you open a single listing plus the two Canadian rules (the stress test and closing-cost cash) most checklists get wrong.